
TS SET 2018: Paper II, Commerce
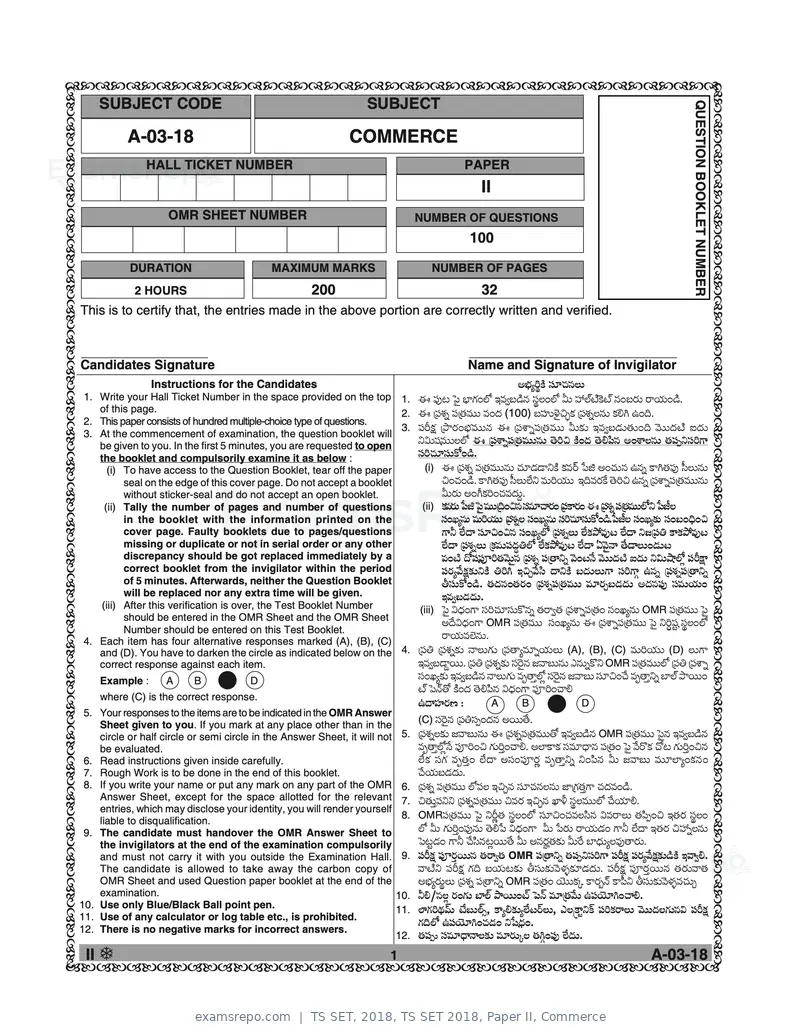
Text of page 1
Subject Code Subject
Question Booklet Number
A-03-18 commerce
hALL tICKET number PaPER
ii
OMR Sheet Number nUMBER OF qUESTIONS
100
dURATION mAXIMUM mARKS nUMBER OF pAGES
2 hOUrs 200 32
This is to certify that, the entries made in the above portion are correctly written and verified.
Candidates Signature Name and Signature of Invigilator
Instructions for the Candidates A¿æýÅǦMìü çÜ*^èþ¯èþË$
1. Write your Hall Ticket Number in the space provided on the top
D ç³#r ò³O ¿êVæü…ÌZ CÐèþÓºyìþ¯èþ çܦ˅ÌZ Ò$ àÌŒýsìýMðüsŒý ¯èþ…ºÆæÿ$ Æ>Äæý$…yìþ.
1.
of this page. D {ç³Ôèý² ç³{™èþÐèþ$$ Ðèþ…§æþ (100) ºçßý$âñýO_eMæü {ç³Ôèý²Ë¯èþ$ MæüÍW E…¨.
2.
2. This paper consists of hundred multiple-choice type of questions.
ç³È„æü {´ëÆæÿ…¿æýÐèþ$$¯èþ D {ç³Ô>²ç³{™èþÐèþ$$ Ò$Mæü$ CÐèþÓºyæþ$™èþ$…¨ Ððþ$$§æþsìý I§æþ$
3. At the commencement of examination, the question booklet will
3.
°Ñ$çÙÐèþ$$ËÌZ D {ç³Ô>²ç³{™èþÐèþ$$¯èþ$ ™ðþÇ_ Mìü…§æþ ™ðþÍí³¯èþ A…Ô>˯èþ$ ™èþç³µ°çÜÇV>
be given to you. In the first 5 minutes, you are requested to open
the booklet and compulsorily examine it as below : çÜÇ^èþ*çÜ$Mø…yìþ.
(i) D {ç³Ôèý² ç³{™èþÐèþ$$¯èþ$ ^èþ*yæþyé°Mìü MæüÐèþÆŠÿ õ³h A…^èþ$¯èþ E¯èþ² M>W™èþç³# ïÜË$¯èþ$
(i) To have access to the Question Booklet, tear off the paper
seal on the edge of this cover page. Do not accept a booklet _…^èþ…yìþ. M>W™èþç³# ïÜË$Ìôý° Ðèþ$ÇÄæý$$ C¨ÐèþÆæÿMóü ™ðþÇ_ E¯èþ² {ç³Ô>²ç³{™èþÐèþ$$¯èþ$
without sticker-seal and do not accept an open booklet. Ò$Ææÿ$ A…XMæüÇ…^èþÐèþ§æþ$ª.
(ii) Tally the number of pages and number of questions (ii) MæüÐèþÆæÿ$ õ³h ò³O Ðèþ$${¨…_¯èþ çÜÐèþ*^éÆæÿ… {ç³M>Ææÿ… D {ç³Ôèý² ç³{™èþÐèþ$$ÌZ° õ³iË
in the booklet with the information printed on the çÜ…Qůèþ$ Ðèþ$ÇÄæý$$ {ç³Ôèý²Ë çÜ…Qůèþ$ çÜÇ^èþ*çÜ$Mø…yìþ.õ³iË çÜ…QÅMæü$ çÜ…º…«¨…_
cover page. Faulty booklets due to pages/questions V>± Ìôý§é çÜ*_…_¯èþ çÜ…QÅÌZ {ç³Ôèý²Ë$ ÌôýMæü´ùÐèþ#r Ìôý§é °f{糆 M>Mæü´ùÐèþ#r
missing or duplicate or not in serial order or any other Ìôý§é {ç³Ôèý²Ë$ {MæüÐèþ$糧æþ®†ÌZ ÌôýMæü´ùÐèþ#r Ìôý§é HÐðþO¯é ™óþyéË$…yæþ$r
discrepancy should be got replaced immediately by a Ðèþ…sìý §øçÙç³NÇ™èþÐðþ$O¯èþ {ç³Ôèý² ç³{™é°² Ððþ…r¯óþ Ððþ$$§æþsìý I§æþ$ °Ñ$ÚëÌZÏ ç³È„>
correct booklet from the invigilator within the period ç³ÆæÿÅÐóþ„æüMæü$°Mìü †ÇW C_aÐóþíÜ §é°Mìü º§æþ$Ë$V> çÜÇV>Y E¯èþ² {ç³Ôèý²ç³{™é°²
of 5 minutes. Afterwards, neither the Question Booklet ¡çÜ$Mø…yìþ. ™èþ§æþ¯èþ…™èþÆæÿ… {ç³Ôèý²ç³{™èþÐèþ$$ Ðèþ*Ææÿaºyæþ§æþ$ A§æþ¯èþç³# çÜÐèþ$Äæý$…
will be replaced nor any extra time will be given. CÐèþÓºyæþ§æþ$.
(iii) After this verification is over, the Test Booklet Number
(iii) ò³O Ñ«§æþ…V> çÜÇ^èþ*çÜ$Mö¯èþ² ™èþÆ>Ó™èþ {ç³Ô>²ç³{™èþ… çÜ…Qůèþ$ OMR ç³{™èþÐèþ$$ ò³O
should be entered in the OMR Sheet and the OMR Sheet
Number should be entered on this Test Booklet.
A§óþÑ«§æþ…V> OMR ç³{™èþÐèþ$$ çÜ…Qůèþ$ D {ç³Ô>²ç³{™èþÐèþ$$ ò³O °Ç®çÙt çܦ˅ÌZ
4. Each item has four alternative responses marked (A), (B), (C)
Æ>Äæý$ÐèþÌñý¯èþ$.
4. {糆 {ç³Ôèý²Mæü$ ¯éË$Væü$ {ç³™éÅÐèþ*²Äæý$Ë$ (A), (B), (C) Ðèþ$ÇÄæý$$ (D) Ë$V>
and (D). You have to darken the circle as indicated below on the
correct response against each item. CÐèþÓºyézÆÿ$$. {糆 {ç³Ôèý²Mæü$ çÜÆðÿO¯èþ fÐéº$¯èþ$ G¯èþ$²Mö° OMR ç³{™èþÐèþ$$ÌZ {糆 {ç³Ô>²
Example : A B C D çÜ…QÅMæü$ CÐèþÓºyìþ¯èþ ¯éË$Væü$ Ðèþ–™é¢ÌZÏ çÜÆðÿO¯èþ fÐéº$ çÜ*_…^óþ Ðèþ–™é¢°² »êÌŒý ´ëÆÿ$$…
sŒý ò³¯Œþ™ø Mìü…§æþ ™ðþÍí³¯èþ Ñ«§æþ…V> ç³NÇ…^éÍ
where (C) is the correct response.
E§éçßýÆæÿ×ý : A B C D
5. Your responses to the items are to be indicated in the OMR Answer
Sheet given to you. If you mark at any place other than in the (C) ç Ü Æð ÿ O ¯ è þ {ç ³ †ç Ü µ…§æ þ ¯è þ AÆÿ$$™ó þ .
circle or half circle or semi circle in the Answer Sheet, it will not 5. {ç³Ôèý²ËMæü$ fÐéº$¯èþ$ D {ç³Ôèý²ç³{™èþÐèþ$$™ø CÐèþÓºyìþ¯èþ OMR ç³{™èþÐèþ$$ ò³O¯èþ CÐèþÓºyìþ¯èþ
be evaluated. Ðèþ–™é¢ÌZϯóþ ç³NÇ…_ Væü$Ç¢…^éÍ. AÌêM>Mæü çÜÐèþ*«§é¯èþ ç³{™èþ… ò³O ÐóþÆöMæü ^ør Væü$Ç¢…_¯èþ
6. Read instructions given inside carefully. ÌôýMæü çÜVæü Ðèþ–™èþ¢… Ìôý§é AçÜ…ç³NÆæÿ~ Ðèþ–™é¢°² °…í³¯èþ Ò$ fÐéº$ Ðèþ$*ÌêÅ…Mæü¯èþ…
7. Rough Work is to be done in the end of this booklet. ^óþÄæý$ºyæþ§æþ$.
8. If you write your name or put any mark on any part of the OMR 6. {ç³Ôèý² ç³{™èþÐèþ$$ ÌZç³Ë C_a¯èþ çÜ*^èþ¯èþ˯èþ$ gê{Væü™èþ¢V> ^èþ§æþÐèþ…yìþ.
Answer Sheet, except for the space allotted for the relevant 7. _™èþ$¢ç³°° {ç³Ôèý²ç³{™èþÐèþ$$ _ÐèþÆæÿ C_a¯èþ Rêä çܦËÐèþ$$ÌZ ^óþÄæý*Í.
entries, which may disclose your identity, you will render yourself
8. OMRç³{™èþÐèþ$$ ò³O °È~™èþ çܦ˅ÌZ çÜ*_…^èþÐèþËíܯèþ ÑÐèþÆ>Ë$ ™èþí³µ…_ C™èþÆæÿ çܦ˅
liable to disqualification.
9. The candidate must handover the OMR Answer Sheet to ÌZ Ò$ Væü$Ç¢…ç³#¯èþ$ ™ðþÍõ³ Ñ«§æþ…V> Ò$ õ³Ææÿ$ Æ>Äæý$yæþ… V>± Ìôý§é C™èþÆæÿ _à²Ë¯èþ$
the invigilators at the end of the examination compulsorily ò³rtyæþ… V>± ^óþíܯèþrÏÆÿ$$™óþ Ò$ A¯èþÆæÿá™èþMæü$ Ò$Æóÿ »ê«§æþ$ÅËÐèþ#™éÆæÿ$.
and must not carry it with you outside the Examination Hall. 9. ç³È„æü ç³NÆæÿ¢Æÿ$$¯èþ ™èþÆ>Ó™èþ OMR ç³{™é°² ™èþç³µ°çÜÇV> ç³È„æü ç³ÆæÿÅÐóþ„æüMæü$yìþMìü CÐéÓÍ.
The candidate is allowed to take away the carbon copy of Ðésìý° ç³È„æü Væü¨ ºÄæý$rMæü$ ¡çÜ$Mæü$ÐðþâæýåMæü*yæþ§æþ$. ç³È„æü ç³NÆæÿ¢Æÿ$$¯èþ ™èþÆæÿ$Ðé™èþ
OMR Sheet and used Question paper booklet at the end of the A¿æýÅÆæÿ$¦Ë$ {ç³Ôèý² ç³{™é°² OMR ç³{™èþ… Äñý$$MæüP M>Ææÿ¾¯Œþ M>ï³° ¡çÜ$Mæü$ÐðþâæýåÐèþ^èþ$a
examination. 10. ±Í/¯èþËÏ Ææÿ…Væü$ »êÌŒý ´ëÆÿ$$…sŒý ò³¯Œþ Ðèþ*{™èþÐóþ$ Eç³Äñý*W…^éÍ.
10. Use only Blue/Black Ball point pen. 11. ÌêVæüÇ£æþÐŒþ$ sôýº$ÌŒýÞ, M>ÅÍMæü$ÅÌôýrÆŠÿË$, GË[M>t°MŠü ç³ÇMæüÆ>Ë$ Ððþ$$§æþËVæü$¯èþÑ ç³È„æü
11. Use of any calculator or log table etc., is prohibited.
12. There is no negative marks for incorrect answers.
Væü¨ÌZ Eç³Äñý*W…^èþyæþ… °õÙ«§æþ….
12. ™èþ糚 çÜÐèþ*«§é¯éËMæü$ Ðèþ*Ææÿ$PË ™èþWY…ç³# Ìôý§æþ$.
II 1 A-03-18
Text of page 2
*A0318*
RE
HE
ITE
WR
T
NO
DO
II 2 A-03-18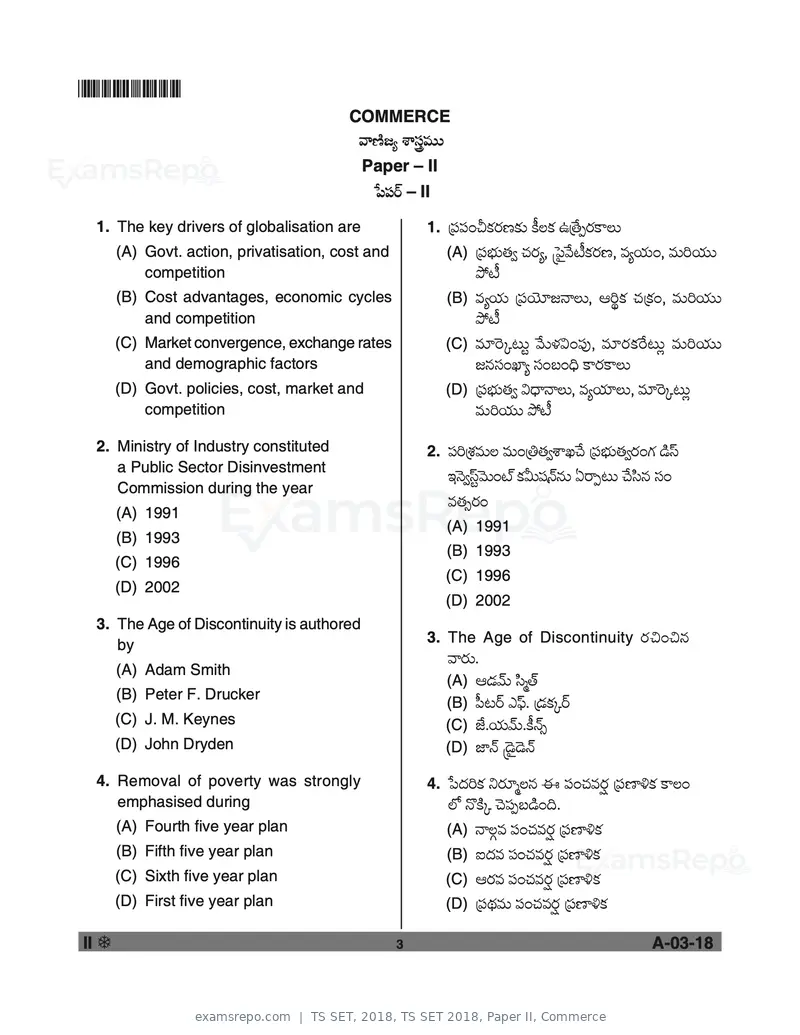
Text of page 3
*A0302*
commerce
þÐé×ìýfÅ Ô>ç܈Ðèþ$$
Paper – II
þõ³ç³ÆŠÿ – II
1. The key drivers of globalisation are 1. {ç³ç³…`MæüÆæÿ×ýMæü$ MîüËMæü E{™óþµÆæÿM>Ë$
(A) Govt. action, privatisation, cost and (A) {糿æý$™èþÓ ^èþÆæÿÅ, [ò³OÐóþsîýMæüÆæÿ×ý, ÐèþÅÄæý$…, Ðèþ$ÇÄæý$$
competition ´ùsîý
(B) Cost advantages, economic cycles (B) ÐèþÅÄæý$ {ç³Äñý*f¯éË$, BǦMæü ^èþ{Mæü…, Ðèþ$ÇÄæý$$
and competition ´ùsîý
(C) Market convergence, exchange rates (C) Ðèþ*ÆðÿPr$t Ðóþ$âæýÑ…ç³#, Ðèþ*ÆæÿMæüÆóÿr$Ï Ðèþ$ÇÄæý$$
and demographic factors f¯èþçÜ…RêÅ çÜ…º…«¨ M>ÆæÿM>Ë$
(D) Govt. policies, cost, market and (D) {糿æý$™èþÓ Ñ«§é¯éË$, ÐèþÅÄæý*Ë$, Ðèþ*ÆðÿPr$Ï
competition Ðèþ$ÇÄæý$$ ´ùsîý
2. Ministry of industry constituted 2. ç³Ç{ÔèýÐèþ$Ë Ðèþ$…{†™èþÓÔ>Q^óþ {糿æý$™èþÓÆæÿ…Væü yìþ‹Ü
a public sector disinvestment
C¯ðþÓ‹ÜtÐðþ$…sŒý MæüÒ$çÙ¯Œþ¯èþ$ HÆ>µr$ ^óþíܯèþ çÜ…
commission during the year
Ðèþ™èþÞÆæÿ…
(A) 1991
(A) 1991
(B) 1993
(B) 1993
(C) 1996
(C) 1996
(D) 2002
(D) 2002
3. The Age of Discontinuity is authored
by 3. The Age of Discontinuity Ææÿ_…_¯èþ
ÐéÆæÿ$.
(A) Adam Smith
(A) ByæþÐŒþ$ íÜÙŒþ
(B) Peter F. Drucker
(B) ï³rÆŠÿ G‹œ. {yæþMæüPÆŠÿ
(C) J. M. Keynes (C) gôý.Äæý$ÐŒþ$.Mîü¯ŒþÞ
(D) John Dryden (D) gꯌþ [yðþOyðþ¯Œþ
4. Removal of poverty was strongly 4. õ³§æþÇMæü °Ææÿ*Ã˯èþ D ç³…^èþÐèþÆæÿÛ {ç³×êãMæü M>Ë…
emphasised during ÌZ ¯öMìüP ^ðþç³µºyìþ…¨.
(A) Fourth five year plan (A) ¯éËYÐèþ ç³…^èþÐèþÆæÿÛ {ç³×êãMæü
(B) Fifth five year plan (B) I§æþÐèþ ç³…^èþÐèþÆæÿÛ {ç³×êãMæü
(C) Sixth five year plan (C) BÆæÿÐèþ ç³…^èþÐèþÆæÿÛ {ç³×êãMæü
(D) First five year plan (D) {ç³£æþÐèþ$ ç³…^èþÐèþÆæÿÛ {ç³×êãMæü
II 3 A-03-18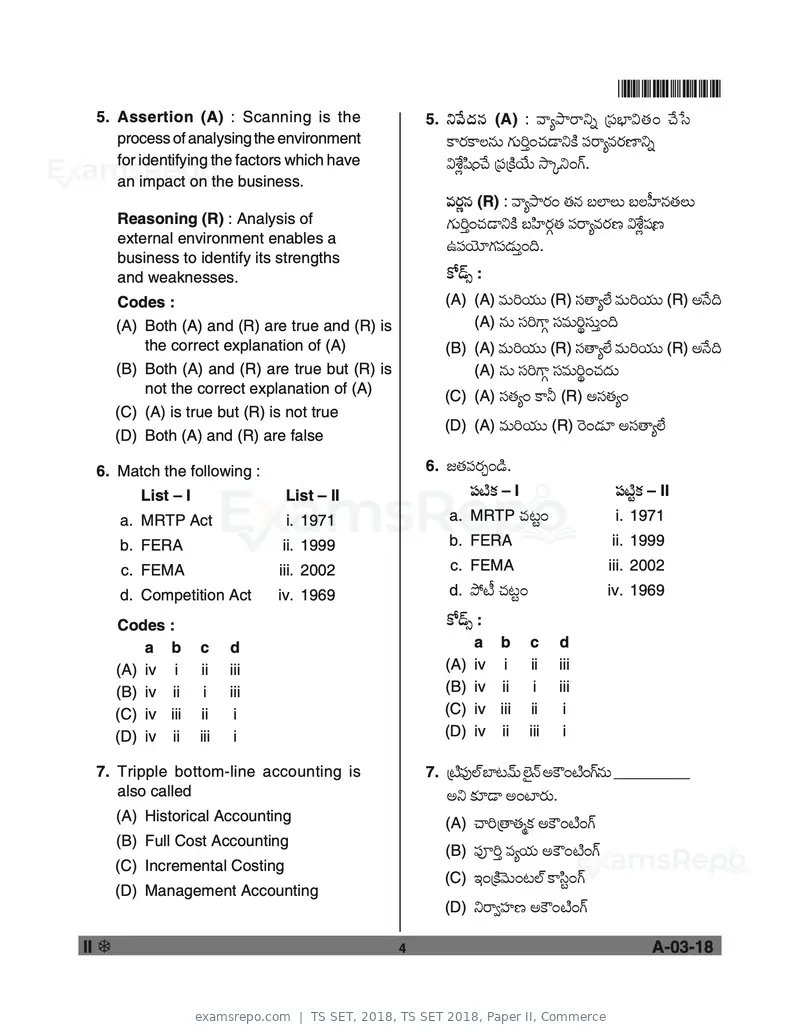
Text of page 4
*A0302*
5. Assertion (A) : Scanning is the 5. °Ðó þ §æ þ¯èþ (A) : ÐéÅ´ëÆ>°² {糿êÑ™èþ… ^óþõÜ
process of analysing the environment M>ÆæÿM>˯èþ$ Væü$Ç¢…^èþyé°Mìü ç³Æ>ÅÐèþÆæÿ×ê°²
for identifying the factors which have ÑÔóýÏíÙ…^óþ {ç³{MìüÄôý$ ÝëP°…VŠü.
an impact on the business.
ÐèþÆæÿ~¯èþ (R) : ÐéÅ´ëÆæÿ… ™èþ¯èþ ºÌêË$ ºËïßý¯èþ™èþË$
Reasoning (R) : Analysis of Væü$Ç¢…^èþyé°Mìü ºíßýÆæÿY™èþ ç³Æ>ÅÐèþÆæÿ×ý ÑÔóýÏçÙ×ý
external environment enables a Eç³Äñý*Væüç³yæþ$¢…¨.
business to identify its strengths
and weaknesses. MøyŠþÞ :
Codes : (A) (A) Ðèþ$ÇÄæý$$ (R) çÜ™éÅÌôý Ðèþ$ÇÄæý$$ (R) A¯óþ¨
(A) Both (A) and (R) are true and (R) is (A) ¯èþ$ çÜÇV>Y çÜÐèþ$ǦçÜ$¢…¨
the correct explanation of (A) (B) (A) Ðèþ$ÇÄæý$$ (R) çÜ™éÅÌôý Ðèþ$ÇÄæý$$ (R) A¯óþ¨
(B) Both (A) and (R) are true but (R) is (A) ¯èþ$ çÜÇV>Y çÜÐèþ$Ǧ…^èþ§æþ$
not the correct explanation of (A) (C) (A) çÜ™èþÅ… M>± (R) AçÜ™èþÅ…
(C) (A) is true but (R) is not true
(D) (A) Ðèþ$ÇÄæý$$ (R) Æðÿ…yæþ* AçÜ™éÅÌôý
(D) Both (A) and (R) are false
6. Match the following : 6. f™èþç³Ææÿa…yìþ.
List – I List – II ç³sìýMæü – I ç³sìýtMæü – II
a. MRTP Act i. 1971 a. MRTP ^èþrt… i. 1971
b. FERA ii. 1999 b. FERA ii. 1999
c. FEMA iii. 2002 c. FEMA iii. 2002
d. Competition Act iv. 1969 d. ´ùsîý ^èþrt… iv. 1969
Codes : MøyŠþÞ :
a b c d a b c d
(A) iv i ii iii (A) iv i ii iii
(B) iv ii i iii (B) iv ii i iii
(C) iv iii ii i (C) iv iii ii i
(D) iv ii iii i (D) iv ii iii i
7. Tripple bottom-line accounting is 7. {sìýç³#ÌŒý »êrÐŒþ$ ÌñýO¯Œþ AMú…sìý…VŠü¯èþ$ _________
also called A° Mæü*yé A…sêÆæÿ$.
(A) Historical Accounting (A) ^éÇ{™é™èþÃMæü AMú…sìý…VŠü
(B) Full Cost Accounting
(B) ç³NÇ¢ ÐèþÅÄæý$ AMú…sìý…VŠü
(C) Incremental Costing
(C) C…{MìüÐðþ$…rÌŒý M>íÜt…VŠü
(D) Management Accounting
(D) °Æ>Óçßý×ý AMú…sìý…VŠü
II 4 A-03-18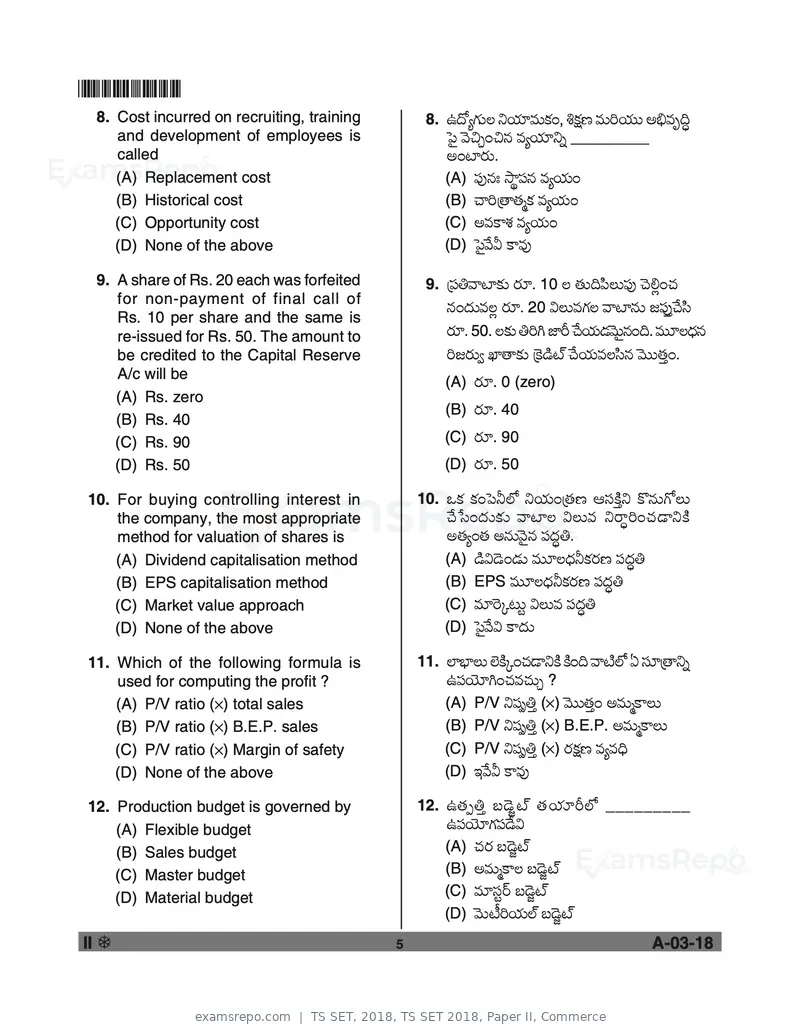
Text of page 5
*A0302*
8. Cost incurred on recruiting, training 8. E§øÅVæü$Ë °Äæý*Ðèþ$Mæü…, Õ„æü×ý Ðèþ$ÇÄæý$$ AÀÐèþ–¨®
and development of employees is ò³O Ððþ_a…_¯èþ ÐèþÅÄæý*°² _________
called A…sêÆæÿ$.
(A) Replacement cost (A) ç³#¯èþ@ Ýë¦ç³¯èþ ÐèþÅÄæý$…
(B) Historical cost (B) ^éÇ{™é™èþÃMæü ÐèþÅÄæý$…
(C) Opportunity cost (C) AÐèþM>Ôèý ÐèþÅÄæý$…
(D) None of the above (D) ò³OÐóþÒ M>Ðèþ#
9. A share of Rs. 20 each was forfeited 9. {糆ÐésêMæü$ Ææÿ*. 10 Ë ™èþ$¨í³Ë$ç³# ^ðþÍÏ…^èþ
for non-payment of final call of
Rs. 10 per share and the same is
¯èþ…§æþ$ÐèþËÏ Ææÿ*. 20 ÑË$ÐèþVæüË Ðésê¯èþ$ fç³#¢^óþíÜ
re-issued for Rs. 50. The amount to Ææÿ*. 50. ËMæü$ †ÇW gêÈ ^óþÄæý$yæþÐðþ$O¯èþ…¨. Ðèþ$*Ë«§æþ¯èþ
be credited to the Capital Reserve ÇfÆæÿ$Ó Rê™éMæü$ {MðüyìþsŒý ^óþÄæý$ÐèþËíܯèþ Ððþ$$™èþ¢….
A/c will be (A) Ææÿ*. 0 (zero)
(A) Rs. zero
(B) Ææÿ*. 40
(B) Rs. 40
(C) Rs. 90 (C) Ææÿ*. 90
(D) Rs. 50 (D) Ææÿ*. 50
10. For buying controlling interest in 10. JMæü Mæü…ò³±ÌZ °Äæý$…{™èþ×ý BçÜMìü¢° Mö¯èþ$VøË$
the company, the most appropriate ^óþõÜ…§æþ$Mæü$ ÐésêË ÑË$Ðèþ °Æ>®Ç…^èþyé°Mìü
method for valuation of shares is A™èþÅ…™èþ A¯èþ$ÐðþO¯èþ 糧æþ®†.
(A) Dividend capitalisation method (A) yìþÑyðþ…yæþ$ Ðèþ$*Ë«§æþ±MæüÆæÿ×ý 糧æþ®†
(B) EPS capitalisation method (B) EPS Ðèþ$*Ë«§æþ±MæüÆæÿ×ý 糧æþ®†
(C) Market value approach (C) Ðèþ*ÆðÿPr$t ÑË$Ðèþ 糧æþ®†
(D) None of the above (D) ò³OÐóþÑ M>§æþ$
11. Which of the following formula is 11. Ìê¿êË$ ÌñýMìüP…^èþyé°Mìü Mìü…¨ ÐésìýÌZ H çÜ*{™é°²
used for computing the profit ? Eç³Äñý*W…^èþÐèþ^èþ$a ?
(A) P/V ratio (×) total sales (A) P/V °çÙµ†¢ (×) Ððþ$$™èþ¢… AÐèþ$ÃM>Ë$
(B) P/V ratio (×) B.E.P. sales (B) P/V °çÙµ†¢ (×) B.E.P. AÐèþ$ÃM>Ë$
(C) P/V ratio (×) Margin of safety (C) P/V °çÙµ†¢ (×) Ææÿ„æü×ý ÐèþÅÐèþ«¨
(D) None of the above (D) CÐóþÒ M>Ðèþ#
12. Production budget is governed by 12. E™è þ µ†¢ ºyð þ j s Œ ý ™è þ Äæ ý *ÈÌZ _________
(A) Flexible budget Eç³Äñý*Væüç³yóþÑ
(B) Sales budget (A) ^èþÆæÿ ºyðþjsŒý
(C) Master budget (B) AÐèþ$ÃM>Ë ºyðþjsŒý
(D) Material budget (C) Ðèþ*çÜtÆŠÿ ºyðþjsŒý
(D) Ððþ$sîýÇÄæý$ÌŒý ºyðþjsŒý
II 5 A-03-18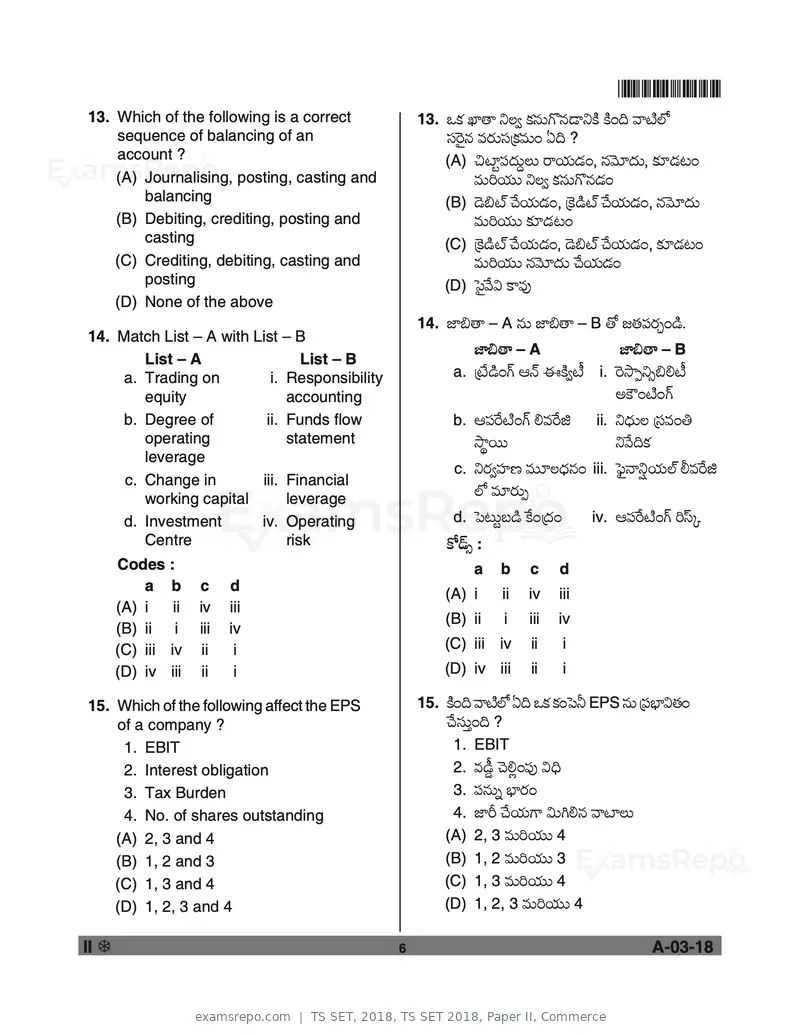
Text of page 6
*A0302*
13. Which of the following is a correct 13. JMæü Rê™é °ËÓ Mæü¯èþ$Vö¯èþyé°Mìü Mìü…¨ ÐésìýÌZ
sequence of balancing of an çÜÆðÿO¯èþ ÐèþÆæÿ$çÜ{MæüÐèþ$… H¨ ?
account ? (A) _sêt糧æþ$ªË$ Æ>Äæý$yæþ…, ¯èþÐðþ*§æþ$, Mæü*yæþr…
(A) Journalising, posting, casting and Ðèþ$ÇÄæý$$ °ËÓ Mæü¯èþ$Vö¯èþyæþ…
balancing (B) yðþ¼sŒý ^óþÄæý$yæþ…, {MðüyìþsŒý ^óþÄæý$yæþ…, ¯èþÐðþ*§æþ$
(B) Debiting, crediting, posting and Ðèþ$ÇÄæý$$ Mæü*yæþr…
casting (C) {MðüyìþsŒý ^óþÄæý$yæþ…, yðþ¼sŒý ^óþÄæý$yæþ…, Mæü*yæþr…
(C) Crediting, debiting, casting and Ðèþ$ÇÄæý$$ ¯èþÐðþ*§æþ$ ^óþÄæý$yæþ…
posting (D) ò³OÐóþÑ M>Ðèþ#
(D) None of the above
14. gê¼™é – A ¯èþ$ gê¼™é – B ™ø f™èþç³Ææÿa…yìþ.
14. Match List – A with List – B
List – A List – B
gê¼™é – A gê¼™é – B
a. Trading on i. Responsibility a. {sôýyìþ…VŠü B¯Œþ DMìüÓsîý i. ÆðÿÝëµ°Þ¼Ísîý
equity accounting AMú…sìý…VŠü
b. Degree of ii. Funds flow b. Bç³Æóÿsìý…VŠü ÍÐèþÆóÿh ii. °«§æþ$Ë {çÜÐèþ…†
operating statement Ýë¦Æÿ$$ °Ðóþ¨Mæü
leverage
c. °ÆæÿÓçßý×ý Ðèþ$*Ë«§æþ¯èþ… iii. òœO¯é°ÛÄæý$ÌŒý ÎÐèþÆóÿh
c. Change in iii. Financial
ÌZ Ðèþ*Ææÿ$µ
working capital leverage
d. Investment iv. Operating d. ò³r$tºyìþ Móü…{§æþ… iv. Bç³Æóÿsìý…VŠü Ç‹ÜP
centre risk MøyŠþÞ :
Codes : a b c d
a b c d
(A) i ii iv iii
(A) i ii iv iii
(B) ii i iii iv
(B) ii i iii iv
(C) iii iv ii i (C) iii iv ii i
(D) iv iii ii i (D) iv iii ii i
15. Which of the following affect the EPS 15. Mìü…¨ ÐésìýÌZ H¨ JMæü Mæü…ò³± EPS ¯èþ$ {糿êÑ™èþ…
of a company ? ^óþçÜ$¢…¨ ?
1. EBIT 1. EBIT
2. Interest obligation 2. Ðèþyîþz ^ðþÍÏ…ç³# Ñ«¨
3. Tax Burden 3. 糯èþ$² ¿êÆæÿ…
4. No. of shares outstanding 4. gêÈ ^óþÄæý$V> Ñ$Wͯèþ ÐésêË$
(A) 2, 3 and 4 (A) 2, 3 Ðèþ$ÇÄæý$$ 4
(B) 1, 2 and 3 (B) 1, 2 Ðèþ$ÇÄæý$$ 3
(C) 1, 3 and 4 (C) 1, 3 Ðèþ$ÇÄæý$$ 4
(D) 1, 2, 3 and 4 (D) 1, 2, 3 Ðèþ$ÇÄæý$$ 4
II 6 A-03-18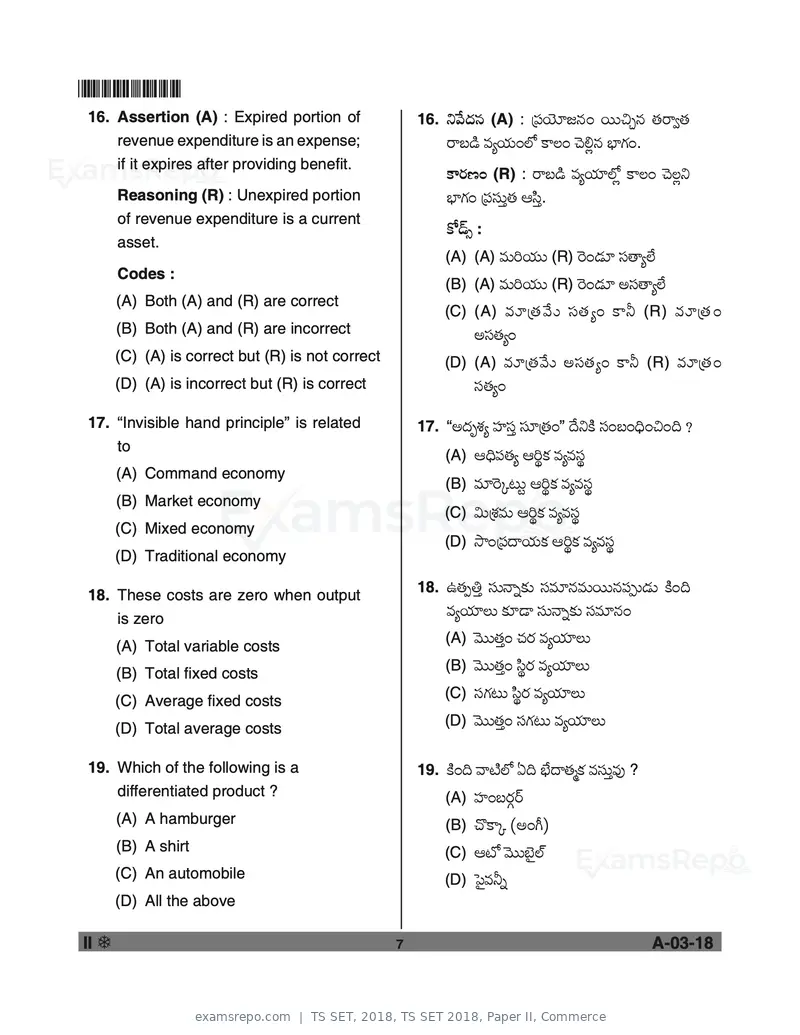
Text of page 7
*A0302*
16. Assertion (A) : Expired portion of 16. °Ðóþ§æþ¯èþ (A) : {ç³Äñý*f¯èþ… Æÿ$$_a¯èþ ™èþÆ>Ó™èþ
revenue expenditure is an expense; Æ>ºyìþ ÐèþÅÄæý$…ÌZ M>Ë… ^ðþÍϯèþ ¿êVæü….
if it expires after providing benefit.
M>Ææÿ×ý… (R) : Æ>ºyìþ ÐèþÅÄæý*ÌZÏ M>Ë… ^ðþËÏ°
Reasoning (R) : Unexpired portion ¿êVæü… {ç³çÜ$¢™èþ BíÜ¢.
of revenue expenditure is a current
MøyŠþÞ :
asset.
(A) (A) Ðèþ$ÇÄæý$$ (R) Æðÿ…yæþ* çÜ™éÅÌôý
Codes :
(B) (A) Ðèþ$ÇÄæý$$ (R) Æðÿ…yæþ* AçÜ™éÅÌôý
(A) Both (A) and (R) are correct
(C) (A) Ðè þ *{™è þ Ðó þ $ ç Ü ™è þ Å… M>± (R) Ðè þ *{™è þ …
(B) Both (A) and (R) are incorrect AçÜ™èþÅ…
(C) (A) is correct but (R) is not correct (D) (A) Ðè þ *{™è þ Ðó þ $ Aç Ü ™è þ Å… M>± (R) Ðè þ *{™è þ …
(D) (A) is incorrect but (R) is correct çÜ™èþÅ…
17. “Invisible hand principle” is related 17. “A§æþ–ÔèýÅ çßýçÜ¢ çÜ*{™èþ…” §óþ°Mìü çÜ…º…«¨…_…¨ ?
to
(A) B«¨ç³™èþÅ BǦMæü ÐèþÅÐèþçܦ
(A) Command economy
(B) Ðèþ*ÆðÿPr$t BǦMæü ÐèþÅÐèþçܦ
(B) Market economy
(C) Ñ${ÔèýÐèþ$ BǦMæü ÐèþÅÐèþçܦ
(C) Mixed economy
(D) Ýë…{糧éÄæý$Mæü BǦMæü ÐèþÅÐèþçܦ
(D) Traditional economy
18. E™èþµ†¢ çÜ$¯é²Mæü$ çÜÐèþ*¯èþÐèþ$Æÿ$$¯èþ糚yæþ$ Mìü…¨
18. These costs are zero when output
is zero
ÐèþÅÄæý*Ë$ Mæü*yé çÜ$¯é²Mæü$ çÜÐèþ*¯èþ…
(A) Ððþ$$™èþ¢… ^èþÆæÿ ÐèþÅÄæý*Ë$
(A) Total variable costs
(B) Ððþ$$™èþ¢… íܦÆæÿ ÐèþÅÄæý*Ë$
(B) Total fixed costs
(C) çÜVæür$ íܦÆæÿ ÐèþÅÄæý*Ë$
(C) Average fixed costs
(D) Ððþ$$™èþ¢… çÜVæür$ ÐèþÅÄæý*Ë$
(D) Total average costs
19. Which of the following is a 19. Mìü…¨ ÐésìýÌZ H¨ ¿ôý§é™èþÃMæü ÐèþçÜ$¢Ðèþ# ?
differentiated product ? (A) çßý…ºÆæÿYÆŠÿ
(A) A hamburger (B) ^öM>P (A…X)
(B) A shirt (C) BsZ Ððþ$$»ñýOÌŒý
(C) An automobile (D) ò³OÐèþ±²
(D) All the above
II 7 A-03-18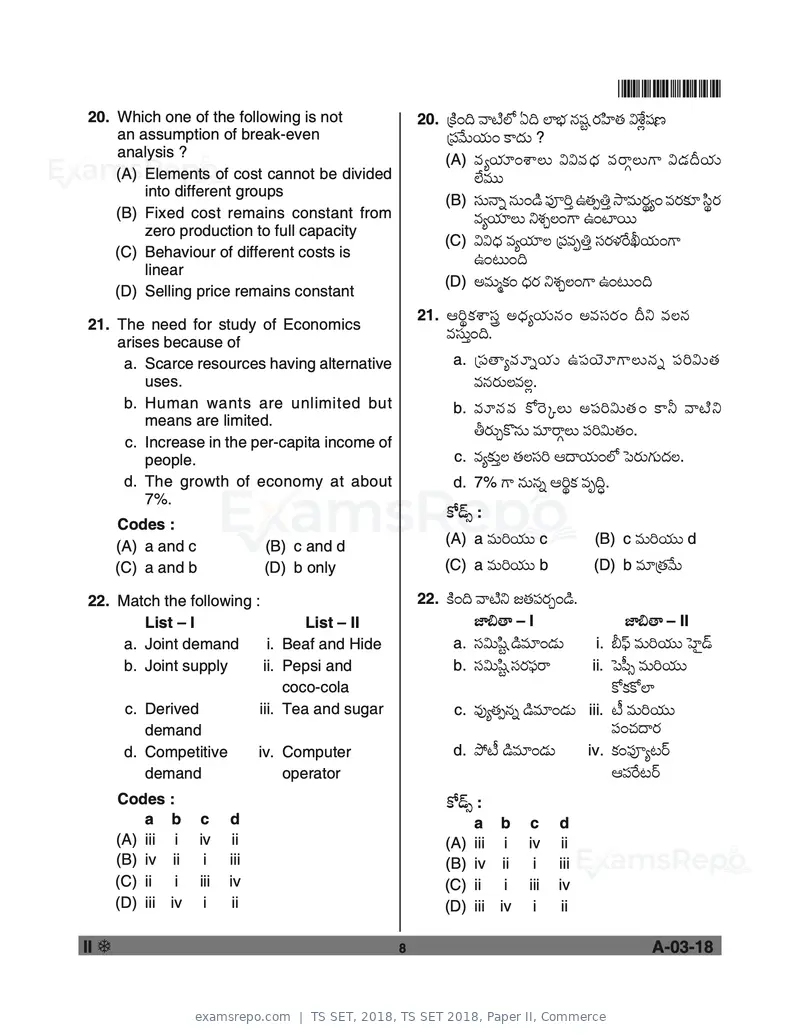
Text of page 8
*A0302*
20. Which one of the following is not 20. {Mìü…¨ ÐésìýÌZ H¨ Ìê¿æý ¯èþçÙt Ææÿíßý™èþ ÑÔóýÏçÙ×ý
an assumption of break-even {ç³Ðóþ$Äæý$… M>§æþ$ ?
analysis ? (A) Ðè þ ÅÄæ ý *…Ô>Ë$ ÑÑÐè þ « § æ þ Ðè þ Æ>Y Ë $V> Ñyæ þ ©Äæ ý $
(A) Elements of cost cannot be divided ÌôýÐèþ$$
into different groups
(B) çÜ$¯é² ¯èþ$…yìþ ç³NÇ¢ E™èþµ†¢ ÝëÐèþ$Ææÿ¦Å… ÐèþÆæÿMæü* íܦÆæÿ
(B) Fixed cost remains constant from ÐèþÅÄæý*Ë$ °ÔèýaË…V> E…sêÆÿ$$
zero production to full capacity
(C) ÑÑ«§æþ ÐèþÅÄæý*Ë {ç³Ðèþ–†¢ çÜÆæÿâæýÆóÿTÄæý$…V>
(C) Behaviour of different costs is E…r$…¨
linear
(D) AÐèþ$ÃMæü… «§æþÆæÿ °ÔèýaË…V> E…r$…¨
(D) Selling price remains constant
21. BǦMæüÔ>ç܈ A«§æþÅÄæý$¯èþ… AÐèþçÜÆæÿ… ©° Ðèþ˯èþ
21. The need for study of economics
arises because of
ÐèþçÜ$¢…¨.
a. Scarce resources having alternative a. {ç ³ ™éÅÐè þ *²Äæ ý $ Eç ³ Äñ ý *V>Ë$¯è þ ² ç ³ ÇÑ$™è þ
uses. Ðèþ¯èþÆæÿ$ËÐèþËÏ.
b. Human wants are unlimited but b. Ðè þ *¯è þ Ðè þ MøÆð ÿ PË$ Aç ³ ÇÑ$™è þ … M>± Ðésì ý °
means are limited.
¡Ææÿ$aMö¯èþ$ Ðèþ*Æ>YË$ ç³ÇÑ$™èþ….
c. Increase in the per-capita income of
people. c. ÐèþÅMæü$¢Ë ™èþËçÜÇ B§éÄæý$…ÌZ ò³Ææÿ$Væü$§æþË.
d. The growth of economy at about d. 7% V> ¯èþ$¯èþ² BǦMæü Ðèþ–¨®.
7%.
MøyŠþÞ :
Codes :
(A) a and c (B) c and d (A) a Ðèþ$ÇÄæý$$ c (B) c Ðèþ$ÇÄæý$$ d
(C) a and b (D) b only (C) a Ðèþ$ÇÄæý$$ b (D) b Ðèþ*{™èþÐóþ$
22. Match the following : 22. Mìü…¨ Ðésìý° f™èþç³Ææÿa…yìþ.
List – I List – II gê¼™é – I gê¼™é – II
a. Joint demand i. Beaf and Hide a. çÜÑ$íÙt yìþÐèþ*…yæþ$ i. ½‹œ Ðèþ$ÇÄæý$$ òßýOyŠþ
b. Joint supply ii. Pepsi and b. çÜÑ$íÙt çÜÆæÿçœÆ> ii. ò³ï³Þ Ðèþ$ÇÄæý$$
coco-cola MøMæüMøÌê
c. Derived iii. Tea and sugar c. Ðèþ#Å™èþµ¯èþ² yìþÐèþ*…yæþ$ iii. sîý Ðèþ$ÇÄæý$$
demand ç³…^èþ§éÆæÿ
d. Competitive iv. Computer d. ´ùsîý yìþÐèþ*…yæþ$ iv. Mæü…ç³NÅrÆŠÿ
demand operator Bç³ÆóÿrÆŠÿ
Codes : MøyŠþÞ :
a b c d a b c d
(A) iii i iv ii (A) iii i iv ii
(B) iv ii i iii (B) iv ii i iii
(C) ii i iii iv (C) ii i iii iv
(D) iii iv i ii (D) iii iv i ii
II 8 A-03-18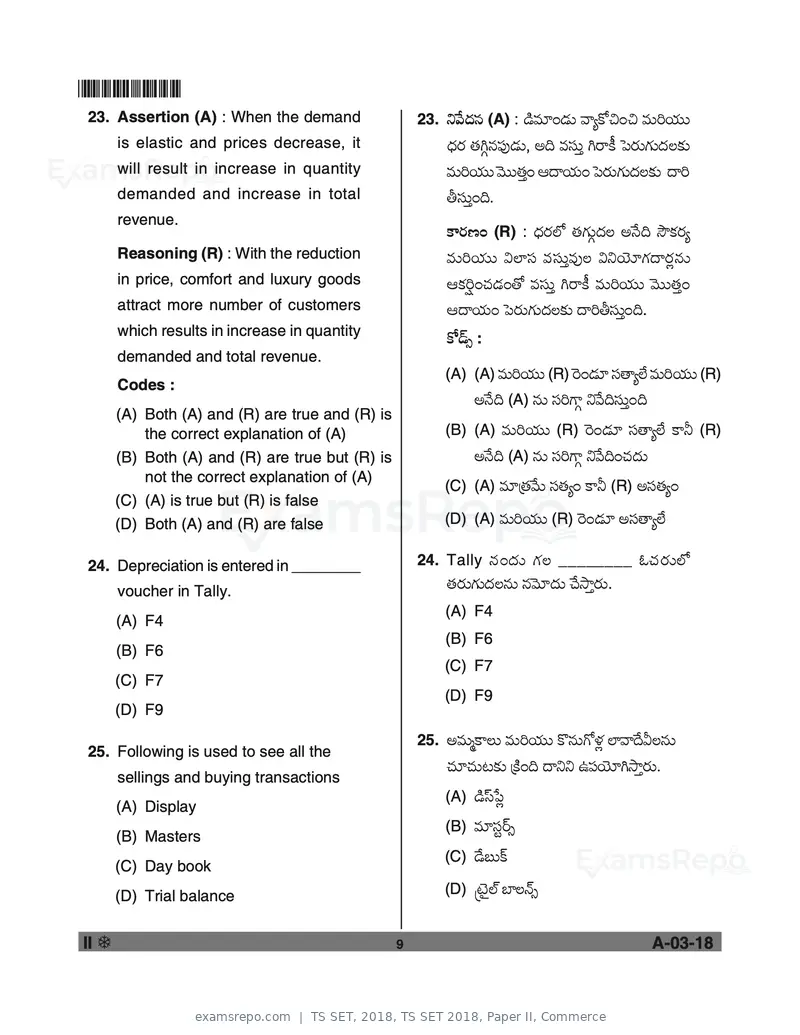
Text of page 9
*A0302*
23. Assertion (A) : When the demand 23. °Ðóþ§æþ¯èþ (A) : yìþÐèþ*…yæþ$ ÐéÅMø_…_ Ðèþ$ÇÄæý$$
is elastic and prices decrease, it «§æþÆæÿ ™èþWY¯èþç³#yæþ$, A¨ ÐèþçÜ$¢ WÆ>Mîü ò³Ææÿ$Væü$§æþËMæü$
will result in increase in quantity Ðèþ$ÇÄæý$$ Ððþ$$™èþ¢… B§éÄæý$… ò³Ææÿ$Væü$§æþËMæü$ §éÇ
demanded and increase in total ¡çÜ$¢…¨.
revenue.
M>Ææÿ×ý… (R) : «§æþÆæÿÌZ ™èþVæü$Y§æþË A¯óþ¨ ÝûMæüÆæÿÅ
Reasoning (R) : With the reduction Ðèþ$ÇÄæý$$ ÑÌêçÜ ÐèþçÜ$¢Ðèþ#Ë Ñ°Äñý*Væü§éÆæÿϯèþ$
in price, comfort and luxury goods BMæüÇÛ…^èþyæþ…™ø ÐèþçÜ$¢ WÆ>Mîü Ðèþ$ÇÄæý$$ Ððþ$$™èþ¢…
attract more number of customers B§éÄæý$… ò³Ææÿ$Væü$§æþËMæü$ §éÇ¡çÜ$¢…¨.
which results in increase in quantity MøyŠþÞ :
demanded and total revenue.
(A) (A) Ðèþ$ÇÄæý$$ (R) Æðÿ…yæþ* çÜ™éÅÌôý Ðèþ$ÇÄæý$$ (R)
Codes :
A¯óþ¨ (A) ¯èþ$ çÜÇV>Y °Ðóþ¨çÜ$¢…¨
(A) Both (A) and (R) are true and (R) is
the correct explanation of (A) (B) (A) Ðèþ$ÇÄæý$$ (R) Æðÿ…yæþ* çÜ™éÅÌôý M>± (R)
(B) Both (A) and (R) are true but (R) is A¯óþ¨ (A) ¯èþ$ çÜÇV>Y °Ðóþ¨…^èþ§æþ$
not the correct explanation of (A)
(C) (A) Ðèþ*{™èþÐóþ$ çÜ™èþÅ… M>± (R) AçÜ™èþÅ…
(C) (A) is true but (R) is false
(D) Both (A) and (R) are false (D) (A) Ðèþ$ÇÄæý$$ (R) Æðÿ…yæþ* AçÜ™éÅÌôý
24. Depreciation is entered in ________ 24. Tally ¯è þ …§æ þ $ Væ ü Ë ________ K^è þ Ææ ÿ $ÌZ
voucher in Tally. ™èþÆæÿ$Væü$§æþ˯èþ$ ¯èþÐðþ*§æþ$ ^óþÝë¢Ææÿ$.
(A) F4
(A) F4
(B) F6
(B) F6
(C) F7
(C) F7
(D) F9
(D) F9
25. AÐèþ$ÃM>Ë$ Ðèþ$ÇÄæý$$ Mö¯èþ$VøâæýÏ ÌêÐé§óþÒ˯èþ$
25. Following is used to see all the
^èþ*^èþ$rMæü$ {Mìü…¨ §é°° Eç³Äñý*WÝë¢Ææÿ$.
sellings and buying transactions
(A) yìþ‹Üõ³Ï
(A) Display
(B) Ðèþ*çÜtÆŠÿÞ
(B) Masters
(C) yóþº$MŠü
(C) Day book
(D) Trial balance (D) [sñýOÌŒý »ê˯ŒþÞ
II 9 A-03-18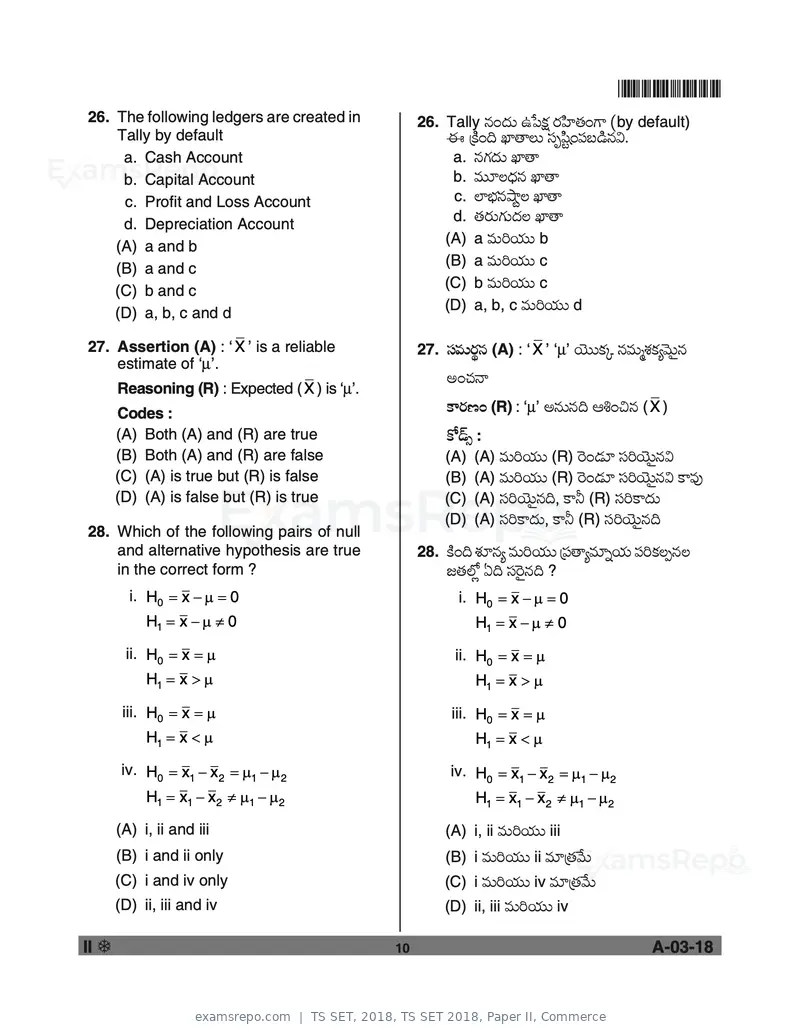
Text of page 10
*A0302*
26. The following ledgers are created in 26. Tally ¯èþ…§æþ$ Eõ³„æü Ææÿíßý™èþ…V> (by default)
Tally by default D {Mìü…¨ Rê™éË$ çÜ–íÙt…糺yìþ¯èþÑ.
a. Cash Account a. ¯èþVæü§æþ$ Rê™é
b. Capital Account b. Ðèþ$*Ë«§æþ¯èþ Rê™é
c. Profit and Loss Account c. Ìê¿æý¯èþÚëtË Rê™é
d. ™èþÆæÿ$Væü$§æþË Rê™é
d. Depreciation Account
(A) a Ðèþ$ÇÄæý$$ b
(A) a and b
(B) a Ðèþ$ÇÄæý$$ c
(B) a and c
(C) b Ðèþ$ÇÄæý$$ c
(C) b and c
(D) a, b, c Ðèþ$ÇÄæý$$ d
(D) a, b, c and d
27. Assertion (A) : ‘ X ’ is a reliable 27. çÜÐèþ$Ææÿ¦¯èþ (A) : ‘ X ’ ‘µ’ Äñý$$MæüP ¯èþÐèþ$ÃÔèýMæüÅÐðþ$O¯èþ
estimate of ‘µ’.
A…^èþ¯é
Reasoning (R) : Expected ( X ) is ‘µ’.
Codes : M>Ææÿ×ý… (R) : ‘µ’ A¯èþ$¯èþ¨ BÕ…_¯èþ ( X )
(A) Both (A) and (R) are true MøyŠþÞ :
(B) Both (A) and (R) are false (A) (A) Ðèþ$ÇÄæý$$ (R) Æðÿ…yæþ* çÜÇÄñý$O¯èþÑ
(C) (A) is true but (R) is false (B) (A) Ðèþ$ÇÄæý$$ (R) Æðÿ…yæþ* çÜÇÄñý$O¯èþÑ M>Ðèþ#
(D) (A) is false but (R) is true (C) (A) çÜÇÄñý$O¯èþ¨, M>± (R) çÜÇM>§æþ$
(D) (A) çÜÇM>§æþ$, M>± (R) çÜÇÄñý$O¯èþ¨
28. Which of the following pairs of null
and alternative hypothesis are true 28. Mìü…¨ Ôèý*¯èþÅ Ðèþ$ÇÄæý$$ {ç³™éÅÐèþ*²Äæý$ ç³ÇMæü˵¯èþË
in the correct form ? f™èþÌZÏ H¨ çÜÆðÿO¯èþ¨ ?
i. H0 = x − µ = 0 i. H0 = x − µ = 0
H1 = x − µ ≠ 0 H1 = x − µ ≠ 0
ii. H0 = x = µ ii. H0 = x = µ
H1 = x > µ H1 = x > µ
iii. H0 = x = µ iii. H0 = x = µ
H1 = x < µ H1 = x < µ
iv. H0 = x1 − x2 = µ1 − µ2 iv. H0 = x1 − x2 = µ1 − µ2
H1 = x1 − x2 ≠ µ1 − µ2 H1 = x1 − x2 ≠ µ1 − µ2
(A) i, ii and iii (A) i, ii Ðèþ$ÇÄæý$$ iii
(B) i and ii only (B) i Ðèþ$ÇÄæý$$ ii Ðèþ*{™èþÐóþ$
(C) i and iv only (C) i Ðèþ$ÇÄæý$$ iv Ðèþ*{™èþÐóþ$
(D) ii, iii and iv (D) ii, iii Ðèþ$ÇÄæý$$ iv
II 10 A-03-18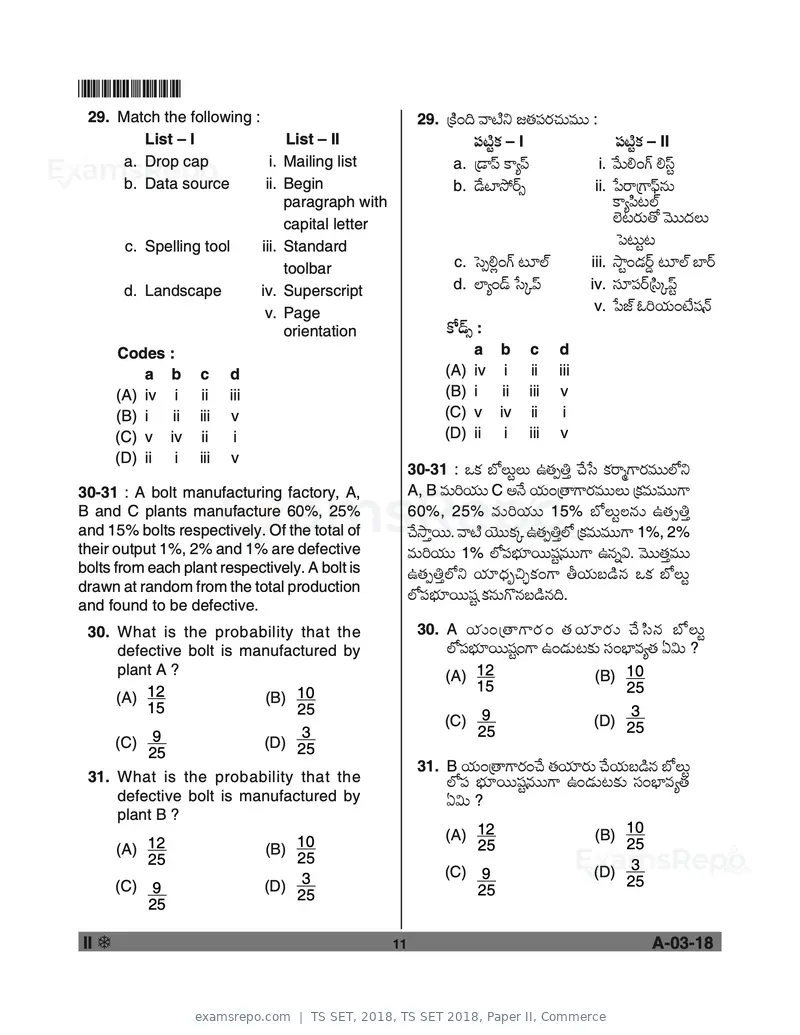
Text of page 11
*A0302*
29. Match the following : 29. {Mìü…¨ Ðésìý° f™èþç³Ææÿ^èþ$Ðèþ$$ :
List – I List – II ç³sìýtMæü – I ç³sìýtMæü – II
a. Drop cap i. Mailing list a. {y鋳 M>Å‹³ i. Ðóþ$Í…VŠü Í‹Üt
b. Data source ii. Begin b. yóþsêÝùÆŠÿÞ ii. õ³Æ>{V>‹œ¯èþ$
paragraph with M>Åí³rÌŒý
capital letter ÌñýrÆæÿ$™ø Ððþ$$§æþË$
c. Spelling tool iii. Standard ò³r$tr
toolbar c. òܵÍÏ…VŠü r*ÌŒý iii. Ýët…yæþÆŠÿz r*ÌŒý »êÆŠÿ
d. Landscape iv. Superscript d. ÌêÅ…yŠþ õÜP‹³ iv. çÜ*ç³ÆŠÿ{íÜP‹³t
v. Page v. õ³gŒý KÇÄæý$…sôýçÙ¯Œþ
orientation MøyŠþÞ :
Codes : a b c d
a b c d (A) iv i ii iii
(A) iv i ii iii (B) i ii iii v
(B) i ii iii v (C) v iv ii i
(C) v iv ii i (D) ii i iii v
(D) ii i iii v
30-31 : JMæü »ZË$tË$ E™èþµ†¢ ^óþõÜ MæüÆ>ÃV>ÆæÿÐèþ$$ÌZ°
30-31 : A bolt manufacturing factory, A, A, B Ðèþ$ÇÄæý$$ C A¯óþ Äæý$…{™éV>ÆæÿÐèþ$$Ë$ {MæüÐèþ$Ðèþ$$V>
B and C plants manufacture 60%, 25% 60%, 25% Ðèþ$ÇÄæý$$ 15% »ZË$t˯èþ$ E™èþµ†¢
and 15% bolts respectively. Of the total of ^óþÝë¢Æÿ$$. Ðésìý Äñý$$MæüP E™èþµ†¢ÌZ {MæüÐèþ$Ðèþ$$V> 1%, 2%
their output 1%, 2% and 1% are defective Ðèþ$ÇÄæý$$ 1% ÌZ糿æý*Æÿ$$çÙtÐèþ$$V> E¯èþ²Ñ. Ððþ$$™èþ¢Ðèþ$$
bolts from each plant respectively. A bolt is E™èþµ†¢ÌZ° Äæý*«§æþ–_eMæü…V> ¡Äæý$ºyìþ¯èþ JMæü »ZË$t
drawn at random from the total production
ÌZ糿æý*Æÿ$$çÙt Mæü¯èþ$Vö¯èþºyìþ¯èþ¨.
and found to be defective.
30. What is the probability that the 30. A Äæ ý $…{™éV>Ææ ÿ … ™è þ Äæ ý *Ææ ÿ $ ^ó þ í Ü ¯è þ »ZË$t
defective bolt is manufactured by ÌZ糿æý*Æÿ$$çÙt…V> E…yæþ$rMæü$ çÜ…¿êÐèþÅ™èþ HÑ$ ?
plant A ? (A) 12 (B) 10
15 25
(A) 12 (B) 10
15 25 3
(C) 9 (D) 25
3 25
(C) 9 (D) 25
25
31. B Äæý$…{™éV>Ææÿ…^óþ ™èþÄæý*Ææÿ$ ^óþÄæý$ºyìþ¯èþ »ZË$t
31. What is the probability that the ÌZç³ ¿æý*Æÿ$$çÙtÐèþ$$V> E…yæþ$rMæü$ çÜ…¿êÐèþÅ™èþ
defective bolt is manufactured by HÑ$ ?
plant B ?
(A) 12 (B) 10
(A) 12 (B) 10 25 25
25 25
(C) 9 (D) 3
(C) 9 (D) 3 25
25
25
25
II 11 A-03-18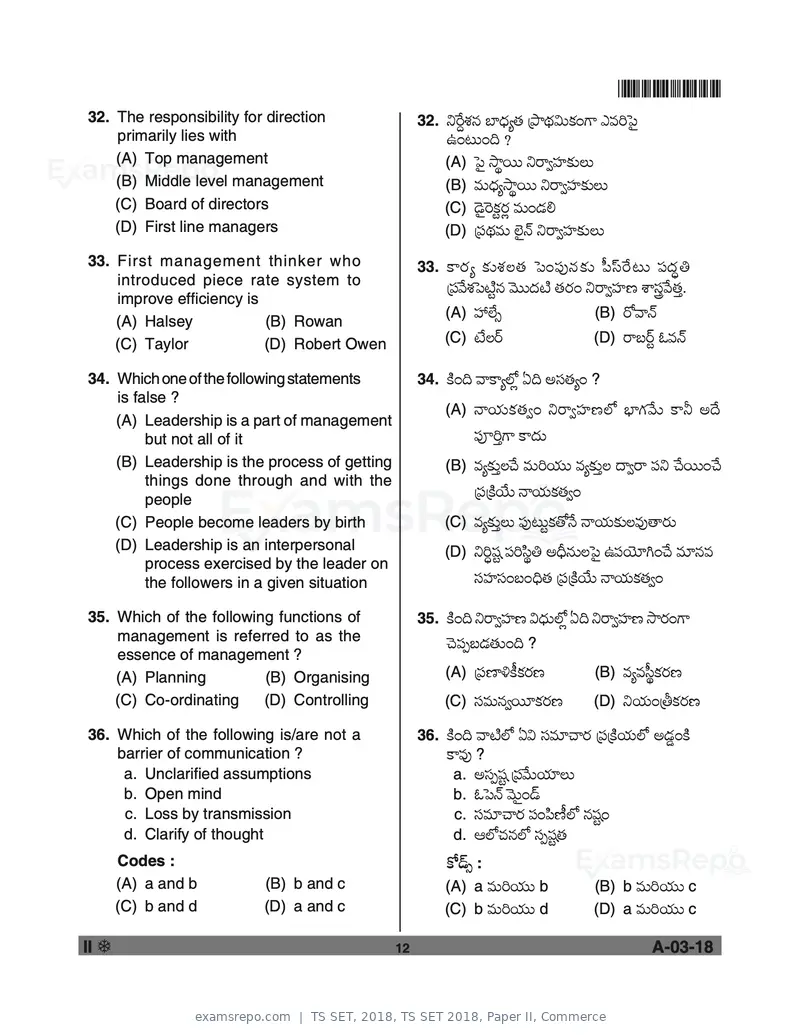
Text of page 12
*A0302*
32. The responsibility for direction 32. °ÆóÿªÔèý¯èþ »ê«§æþÅ™èþ {´ë£æþÑ$Mæü…V> GÐèþÇò³O
primarily lies with E…r$…¨ ?
(A) Top management (A) ò³O Ýë¦Æÿ$$ °Æ>ÓçßýMæü$Ë$
(B) Middle level management (B) Ðèþ$«§æþÅÝë¦Æÿ$$ °Æ>ÓçßýMæü$Ë$
(C) Board of directors (C) yðþOÆðÿMæütÆæÿÏ Ðèþ$…yæþÍ
(D) First line managers (D) {ç³£æþÐèþ$ ÌñýO¯Œþ °Æ>ÓçßýMæü$Ë$
33. First management thinker who 33. M>Ææ ÿ Å Mæ ü $Ôè ý Ë™è þ ò³…ç ³ #¯è þ Mæ ü $ ï ³ ‹ Ü Æó ÿ r$ ç ³ §æ þ ® †
introduced piece rate system to {ç³ÐóþÔèýò³sìýt¯èþ Ððþ$$§æþsìý ™èþÆæÿ… °Æ>Óçßý×ý Ô>ç܈Ðóþ™èþ¢.
improve efficiency is
(A) àÌôýÞ (B) ÆøÐ鯌þ
(A) Halsey (B) Rowan
(C) Taylor (D) Robert Owen (C) sôýËÆŠÿ (D) Æ>ºÆŠÿt KÐèþ¯Œþ
34. Which one of the following statements 34. Mìü…¨ ÐéM>ÅÌZÏ H¨ AçÜ™èþÅ… ?
is false ?
(A) ¯éÄæý$Mæü™èþÓ… °Æ>Óçßý×ýÌZ ¿êVæüÐóþ$ M>± A§óþ
(A) Leadership is a part of management
but not all of it ç³NÇ¢V> M>§æþ$
(B) Leadership is the process of getting (B) ÐèþÅMæü$¢Ë^óþ Ðèþ$ÇÄæý$$ ÐèþÅMæü$¢Ë §éÓÆ> ç³° ^óþÆÿ$$…^óþ
things done through and with the
people
{ç³{MìüÄôý$ ¯éÄæý$Mæü™èþÓ…
(C) People become leaders by birth (C) ÐèþÅMæü$¢Ë$ ç³#r$tMæü™ø¯óþ ¯éÄæý$Mæü$ËÐèþ#™éÆæÿ$
(D) Leadership is an interpersonal (D) °Ç®çÙt ç³Çíܦ† A«©¯èþ$Ëò³O Eç³Äñý*W…^óþ Ðèþ*¯èþÐèþ
process exercised by the leader on
the followers in a given situation çÜçßýçÜ…º…«¨™èþ {ç³{MìüÄôý$ ¯éÄæý$Mæü™èþÓ…
35. Which of the following functions of 35. Mìü…¨ °Æ>Óçßý×ý Ñ«§æþ$ÌZÏ H¨ °Æ>Óçßý×ý ÝëÆæÿ…V>
management is referred to as the ^ðþç³µºyæþ™èþ$…¨ ?
essence of management ?
(A) Planning (B) Organising (A) {ç³×êãMîüMæüÆæÿ×ý (B) ÐèþÅÐèþïܦMæüÆæÿ×ý
(C) Co-ordinating (D) Controlling (C) çÜÐèþ$¯èþÓÆÿ$*MæüÆæÿ×ý (D) °Äæý$…{¡MæüÆæÿ×ý
36. Which of the following is/are not a 36. Mìü…¨ ÐésìýÌZ HÑ çÜÐèþ*^éÆæÿ {ç³{MìüÄæý$ÌZ Ayæþz…Mìü
barrier of communication ? M>Ðèþ# ?
a. Unclarified assumptions a. AçܵçÙt {ç³Ðóþ$Äæý*Ë$
b. Open mind b. Kò³¯Œþ Ððþ$O…yŠþ
c. Loss by transmission c. çÜÐèþ*^éÆæÿ ç³…í³×îýÌZ ¯èþçÙt…
d. Clarify of thought d. BÌZ^èþ¯èþÌZ çܵçÙt™èþ
Codes : MøyŠþÞ :
(A) a and b (B) b and c (A) a Ðèþ$ÇÄæý$$ b (B) b Ðèþ$ÇÄæý$$ c
(C) b and d (D) a and c (C) b Ðèþ$ÇÄæý$$ d (D) a Ðèþ$ÇÄæý$$ c
II 12 A-03-18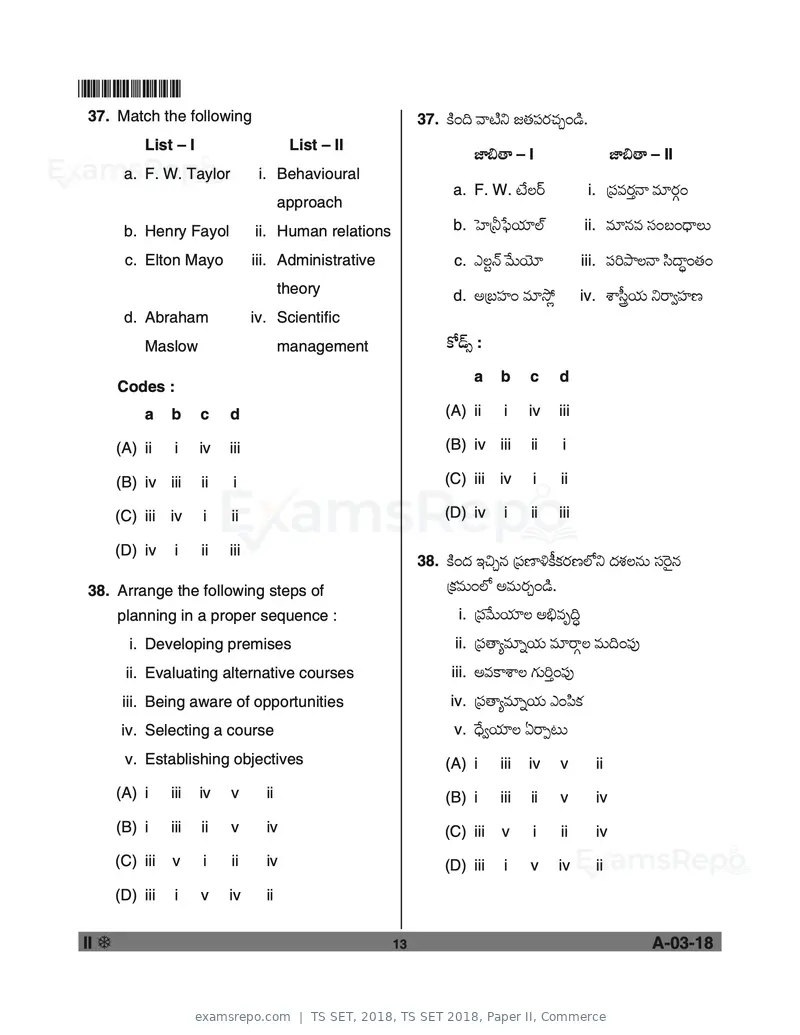
Text of page 13
*A0302*
37. Match the following 37. Mìü…¨ Ðésìý° f™èþç³Ææÿ^èþa…yìþ.
List – I List – II
gê¼™é – I gê¼™é – II
a. F. W. Taylor i. Behavioural
a. F. W. sôýËÆŠÿ i. {ç³ÐèþÆæÿ¢¯é Ðèþ*ÆæÿY…
approach
b. Henry Fayol ii. Human relations b. òßý{±õœÄæý*ÌŒý ii. Ðèþ*¯èþÐèþ çÜ…º…«§éË$
c. Elton Mayo iii. Administrative c. GËt¯Œþ Ðóþ$Äñý* iii. ç³Ç´ë˯é íܧ鮅™èþ…
theory d. A{ºçßý… Ðèþ*ÝùÏ iv. Ô>ï܈Äæý$ °Æ>Óçßý×
d. Abraham iv. Scientific
Maslow management MøyŠþÞ :
a b c d
Codes :
a b c d (A) ii i iv iii
(A) ii i iv iii (B) iv iii ii i
(B) iv iii ii i (C) iii iv i ii
(C) iii iv i ii (D) iv i ii iii
(D) iv i ii iii
38. Mìü…§æþ C_a¯èþ {ç³×êãMîüMæüÆæÿ×ýÌZ° §æþÔèý˯èþ$ çÜÆðÿO¯èþ
38. Arrange the following steps of {MæüÐèþ$…ÌZ AÐèþ$Ææÿa…yìþ.
planning in a proper sequence : i. {ç³Ðóþ$Äæý*Ë AÀÐèþ–¨®
i. Developing premises ii. {ç³™éÅÐèþ*²Äæý$ Ðèþ*Æ>YË Ðèþ$¨…ç³#
ii. Evaluating alternative courses iii. AÐèþM>Ô>Ë Væü$Ç¢…ç³#
iii. Being aware of opportunities iv. {ç³™éÅÐèþ*²Äæý$ G…í³Mæü
iv. Selecting a course v. «§óþÓÄæý*Ë HÆ>µr$
v. Establishing objectives (A) i iii iv v ii
(A) i iii iv v ii (B) i iii ii v iv
(B) i iii ii v iv (C) iii v i ii iv
(C) iii v i ii iv (D) iii i v iv ii
(D) iii i v iv ii
II 13 A-03-18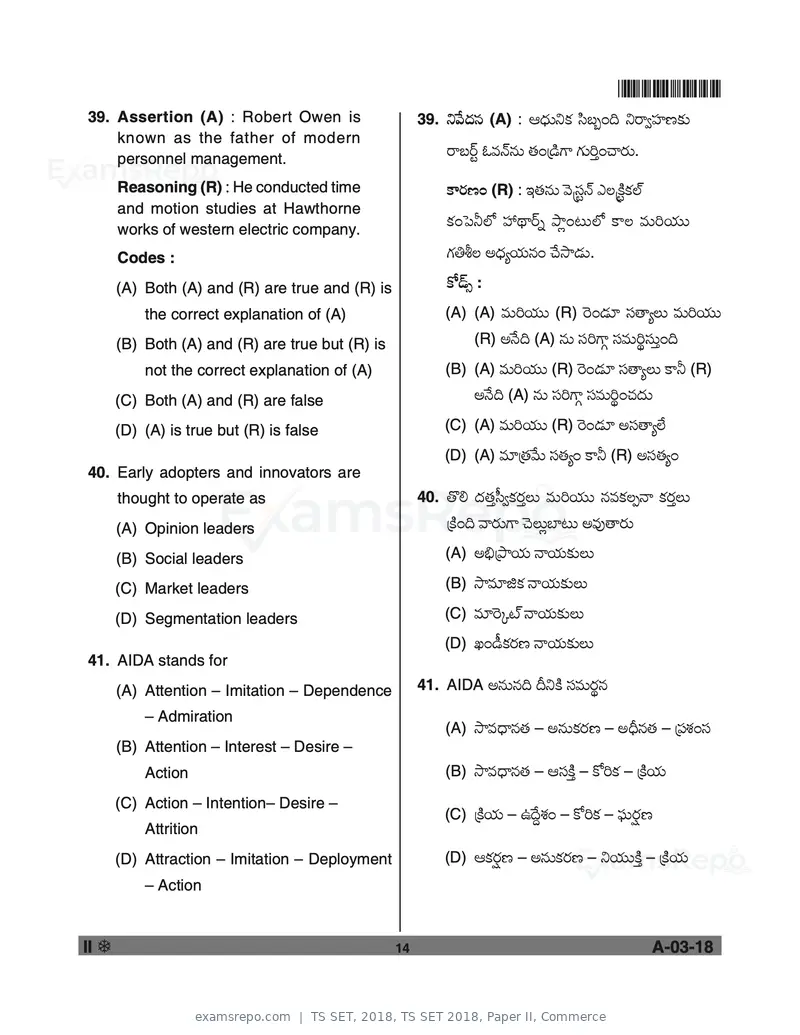
Text of page 14
*A0302*
39. Assertion (A) : Robert Owen is 39. °Ðóþ§æþ¯èþ (A) : B«§æþ$°Mæü íܺ¾…¨ °Æ>Óçßý×ýMæü$
known as the father of modern
personnel management.
Æ>ºÆŠÿt KÐèþ¯Œþ¯èþ$ ™èþ…{yìþV> Væü$Ç¢…^éÆæÿ$.
Reasoning (R) : He conducted time M>Ææÿ×ý… (R) : C™èþ¯èþ$ Ððþ[çÜt¯Œþ GË[MìütMæüÌŒý
and motion studies at Hawthorne
works of western electric company.
Mæü…ò³±ÌZ à£éÆŠÿ² ´ëÏ…r$ÌZ M>Ë Ðèþ$ÇÄæý$$
Codes : Væü†ÖË A«§æþÅÄæý$¯èþ… ^óþÝëyæþ$.
(A) Both (A) and (R) are true and (R) is MøyŠþÞ :
the correct explanation of (A) (A) (A) Ðèþ$ÇÄæý$$ (R) Æðÿ…yæþ* çÜ™éÅË$ Ðèþ$ÇÄæý$$
(B) Both (A) and (R) are true but (R) is (R) A¯óþ¨ (A) ¯èþ$ çÜÇV>Y çÜÐèþ$ǦçÜ$¢…¨
not the correct explanation of (A) (B) (A) Ðèþ$ÇÄæý$$ (R) Æðÿ…yæþ* çÜ™éÅË$ M>± (R)
(C) Both (A) and (R) are false A¯óþ¨ (A) ¯èþ$ çÜÇV>Y çÜÐèþ$Ǧ…^èþ§æþ$
(D) (A) is true but (R) is false (C) (A) Ðèþ$ÇÄæý$$ (R) Æðÿ…yæþ* AçÜ™éÅÌôý
(D) (A) Ðèþ*{™èþÐóþ$ çÜ™èþÅ… M>± (R) AçÜ™èþÅ…
40. Early adopters and innovators are
thought to operate as 40. ™öÍ §æþ™èþ¢ïÜÓMæüÆæÿ¢Ë$ Ðèþ$ÇÄæý$$ ¯èþÐèþMæü˵¯é MæüÆæÿ¢Ë$
(A) Opinion leaders {Mìü…¨ ÐéÆæÿ$V> ^ðþË$Ï»êr$ AÐèþ#™éÆæÿ$
(B) Social leaders (A) AÀ{´ëÄæý$ ¯éÄæý$Mæü$Ë$
(C) Market leaders (B) ÝëÐèþ*hMæü ¯éÄæý$Mæü$Ë$
(D) Segmentation leaders (C) Ðèþ*ÆðÿPsŒý ¯éÄæý$Mæü$Ë$
(D) Q…yîþMæüÆæÿ×ý ¯éÄæý$Mæü$Ë$
41. AIDA stands for
(A) Attention – Imitation – Dependence 41. AIDA A¯èþ$¯èþ¨ ©°Mìü çÜÐèþ$Ææÿ¦¯èþ
– Admiration
(A) ÝëÐèþ«§é¯èþ™èþ – A¯èþ$MæüÆæÿ×ý – A«©¯èþ™èþ – {ç³Ôèý…çÜ
(B) Attention – Interest – Desire –
Action (B) ÝëÐèþ«§é¯èþ™èþ – BçÜMìü¢ – MøÇMæü – {MìüÄæý$
(C) Action – Intention– Desire –
(C) {MìüÄæý$ – E§óþªÔèý… – MøÇMæü – çœ$ÆæÿÛ×ý
Attrition
(D) Attraction – Imitation – Deployment (D) BMæüÆæÿÛ×ý – A¯èþ$MæüÆæÿ×ý – °Äæý$$Mìü¢ – {MìüÄæý$
– Action
II 14 A-03-18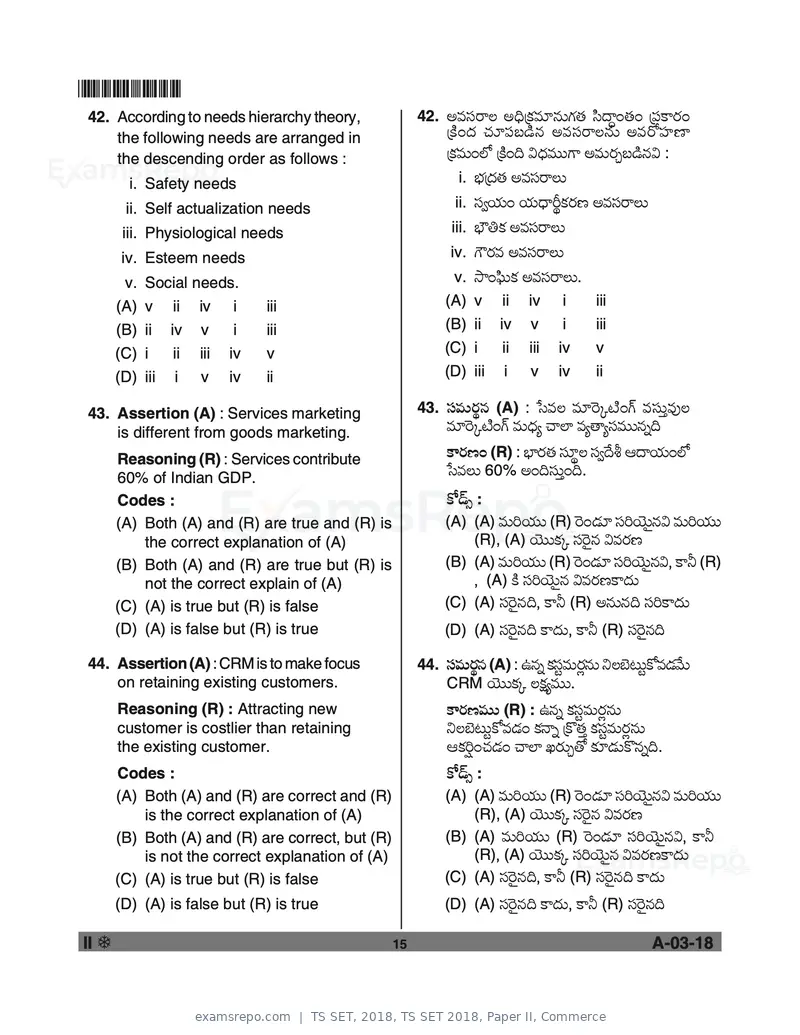
Text of page 15
*A0302*
42. According to needs hierarchy theory, 42. AÐèþçÜÆ>Ë A«¨{MæüÐèþ*¯èþ$Væü™èþ íܧ鮅™èþ… {ç³M>Ææÿ…
the following needs are arranged in {Mìü…§æþ ^èþ*糺yìþ¯èþ AÐèþçÜÆ>˯èþ$ AÐèþÆøçßý×ê
the descending order as follows : {MæüÐèþ$…ÌZ {Mìü…¨ Ñ«§æþÐèþ$$V> AÐèþ$Ææÿaºyìþ¯èþÑ :
i. Safety needs i. ¿æý{§æþ™èþ AÐèþçÜÆ>Ë$
ii. Self actualization needs ii. çÜÓÄæý$… Äæý$«§éȦMæüÆæÿ×ý AÐèþçÜÆ>Ë$
iii. Physiological needs iii. ¿o†Mæü AÐèþçÜÆ>Ë$
iv. Esteem needs iv. VúÆæÿÐèþ AÐèþçÜÆ>Ë$
v. Social needs. v. Ýë…íœ$Mæü AÐèþçÜÆ>Ë$.
(A) v ii iv i iii (A) v ii iv i iii
(B) ii iv v i iii (B) ii iv v i iii
(C) i ii iii iv v (C) i ii iii iv v
(D) iii i v iv ii (D) iii i v iv ii
43. Assertion (A) : Services marketing 43. çÜÐèþ$Ææÿ¦¯èþ (A) : õÜÐèþË Ðèþ*ÆðÿPsìý…VŠü ÐèþçÜ$¢Ðèþ#Ë
is different from goods marketing. Ðèþ*ÆðÿPsìý…VŠü Ðèþ$«§æþÅ ^éÌê ÐèþÅ™éÅçÜÐèþ$$¯èþ²¨
Reasoning (R) : Services contribute M>Ææÿ×ý… (R) : ¿êÆæÿ™èþ çÜ*¦Ë çÜÓ§óþÖ B§éÄæý$…ÌZ
60% of Indian GDP. õÜÐèþË$ 60% A…¨çÜ$¢…¨.
Codes : MøyŠþÞ :
(A) Both (A) and (R) are true and (R) is (A) (A) Ðèþ$ÇÄæý$$ (R) Æðÿ…yæþ* çÜÇÄñý$O¯èþÑ Ðèþ$ÇÄæý$$
the correct explanation of (A) (R), (A) Äñý$$MæüP çÜÆðÿO¯èþ ÑÐèþÆæÿ×ý
(B) Both (A) and (R) are true but (R) is (B) (A) Ðèþ$ÇÄæý$$ (R) Æðÿ…yæþ* çÜÇÄñý$O¯èþÑ, M>± (R)
not the correct explain of (A) , (A) Mìü çÜÇÄñý$O¯èþ ÑÐèþÆæÿ×ýM>§æþ$
(C) (A) is true but (R) is false (C) (A) çÜÆðÿO¯èþ¨, M>± (R) A¯èþ$¯èþ¨ çÜÇM>§æþ$
(D) (A) is false but (R) is true (D) (A) çÜÆðÿO¯èþ¨ M>§æþ$, M>± (R) çÜÆðÿO¯èþ¨ý
44. Assertion (A) : CRM is to make focus 44. çÜÐèþ$Ææÿ¦¯èþ (A) : E¯èþ² MæüçÜtÐèþ$Ææÿϯèþ$ °Ë»ñýr$tMøÐèþyæþÐóþ$
on retaining existing customers. CRM Äñý$$MæüP Ë„æüÅÐèþ$$.
Reasoning (R) : Attracting new M>Ææÿ×ýÐèþ$$ (R) : E¯èþ² MæüçÜtÐèþ$Ææÿϯèþ$
customer is costlier than retaining °Ë»ñýr$tMøÐèþyæþ… Mæü¯é² {Mö™èþ¢ MæüçÜtÐèþ$Ææÿϯèþ$
the existing customer. BMæüÇÛ…^èþyæþ… ^éÌê QÆæÿ$a™ø Mæü*yæþ$Mö¯èþ²¨.
Codes : MøyŠþÞ :
(A) Both (A) and (R) are correct and (R) (A) (A) Ðèþ$ÇÄæý$$ (R) Æðÿ…yæþ* çÜÇÄñý$O¯èþÑ Ðèþ$ÇÄæý$$
is the correct explanation of (A) (R), (A) Äñý$$MæüP çÜÆðÿO¯èþ ÑÐèþÆæÿ×ý
(B) Both (A) and (R) are correct, but (R) (B) (A) Ðèþ$ÇÄæý$$ (R) Æðÿ…yæþ* çÜÇÄñý$O¯èþÑ, M>±
is not the correct explanation of (A) (R), (A) Äñý$$MæüP çÜÇÄñý$O¯èþ ÑÐèþÆæÿ×ýM>§æþ$
(C) (A) is true but (R) is false (C) (A) çÜÆðÿO¯èþ¨, M>± (R) çÜÆðÿO¯èþ¨ M>§æþ$
(D) (A) is false but (R) is true (D) (A) çÜÆðÿO¯èþ¨ M>§æþ$, M>± (R) çÜÆðÿO¯èþ¨
II 15 A-03-18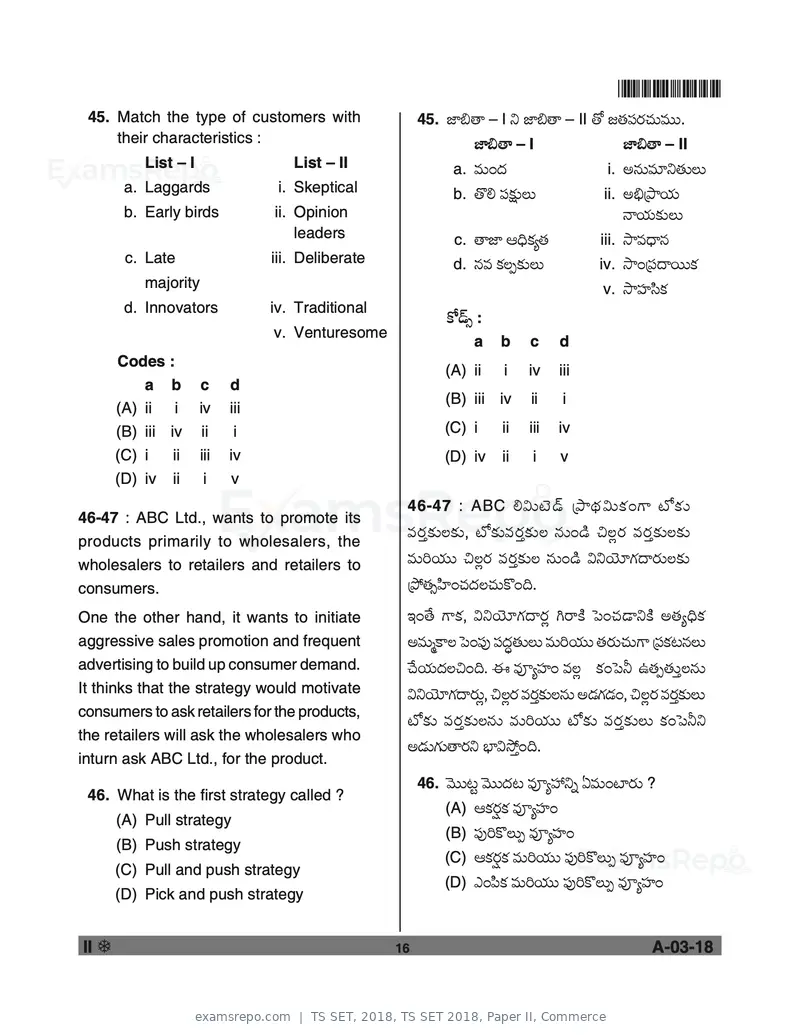
Text of page 16
*A0302*
45. Match the type of customers with 45. gê¼™é – I ° gê¼™é – II ™ø f™èþç³Ææÿ^èþ$Ðèþ$$.
their characteristics : gê¼™é – I gê¼™é – II
List – I List – II a. Ðèþ$…§æþ i. A¯èþ$Ðèþ*°™èþ$Ë$
a. Laggards i. Skeptical b. ™öÍ ç³„æü$Ë$ ii. AÀ{´ëÄæý$
b. Early birds ii. Opinion ¯éÄæý$Mæü$Ë$
leaders c. ™égê B«¨MæüÅ™èþ iii. ÝëÐèþ«§é¯èþ
c. Late iii. Deliberate d. ¯èþÐèþ Mæü˵Mæü$Ë$ iv. Ýë…{糧éÆÿ$$Mæü
majority v. ÝëçßýíÜMæü
d. Innovators iv. Traditional
MøyŠþÞ :
v. Venturesome
a b c d
Codes :
(A) ii i iv iii
a b c d
(B) iii iv ii i
(A) ii i iv iii
(B) iii iv ii i (C) i ii iii iv
(C) i ii iii iv (D) iv ii i v
(D) iv ii i v
46-47 : ABC ÍÑ$sñ ý yŠ þ {´ë£æ þ Ñ$Mæ ü …V> sZMæ ü $
46-47 : ABC Ltd., wants to promote its
products primarily to wholesalers, the
ÐèþÆæÿ¢Mæü$ËMæü$, sZMæü$ÐèþÆæÿ¢Mæü$Ë ¯èþ$…yìþ _ËÏÆæÿ ÐèþÆæÿ¢Mæü$ËMæü$
wholesalers to retailers and retailers to Ðèþ$ÇÄæý$$ _ËÏÆæÿ ÐèþÆæÿ¢Mæü$Ë ¯èþ$…yìþ Ñ°Äñý*Væü§éÆæÿ$ËMæü$
consumers. {´ù™èþÞíßý…^èþ§æþË^èþ$Mö…¨.
One the other hand, it wants to initiate C…™óþ V>Mæü, Ñ°Äñý*Væü§éÆæÿÏ WÆ>Mìü ò³…^èþyé°Mìü A™èþÅ«¨Mæü
aggressive sales promotion and frequent AÐèþ$ÃM>Ë ò³…ç³# 糧æþ®™èþ$Ë$ Ðèþ$ÇÄæý$$ ™èþÆæÿ$^èþ$V> {ç³Mæür¯èþË$
advertising to build up consumer demand. ^óþÄæý$§æþË_…¨. D ÐèþNÅçßý… ÐèþËÏ Mæü…ò³± E™èþµ™èþ$¢Ë¯èþ$
It thinks that the strategy would motivate Ñ°Äñý*Væü§éÆæÿ$Ï, _ËÏÆæÿ ÐèþÆæÿ¢Mæü$˯èþ$ AyæþVæüyæþ…, _ËÏÆæÿ ÐèþÆæÿ¢Mæü$Ë$
consumers to ask retailers for the products,
sZMæü$ ÐèþÆæÿ¢Mæü$˯èþ$ Ðèþ$ÇÄæý$$ sZMæü$ ÐèþÆæÿ¢Mæü$Ë$ Mæü…ò³±°
the retailers will ask the wholesalers who
Ayæþ$Væü$™éÆæÿ° ¿êÑÝù¢…¨.
inturn ask ABC Ltd., for the product.
46. Ððþ$$rt Ððþ$$§æþr ÐèþNÅà°² HÐèþ$…sêÆæÿ$ ?
46. What is the first strategy called ?
(A) BMæüÆæÿÛMæü ÐèþNÅçßý…
(A) Pull strategy
(B) ç³#ÇMöË$µ ÐèþNÅçßý…
(B) Push strategy
(C) BMæüÆæÿÛMæü Ðèþ$ÇÄæý$$ ç³#ÇMöË$µ ÐèþNÅçßý…
(C) Pull and push strategy
(D) G…í³Mæü Ðèþ$ÇÄæý$$ ç³#ÇMöË$µ ÐèþNÅçßý…
(D) Pick and push strategy
II 16 A-03-18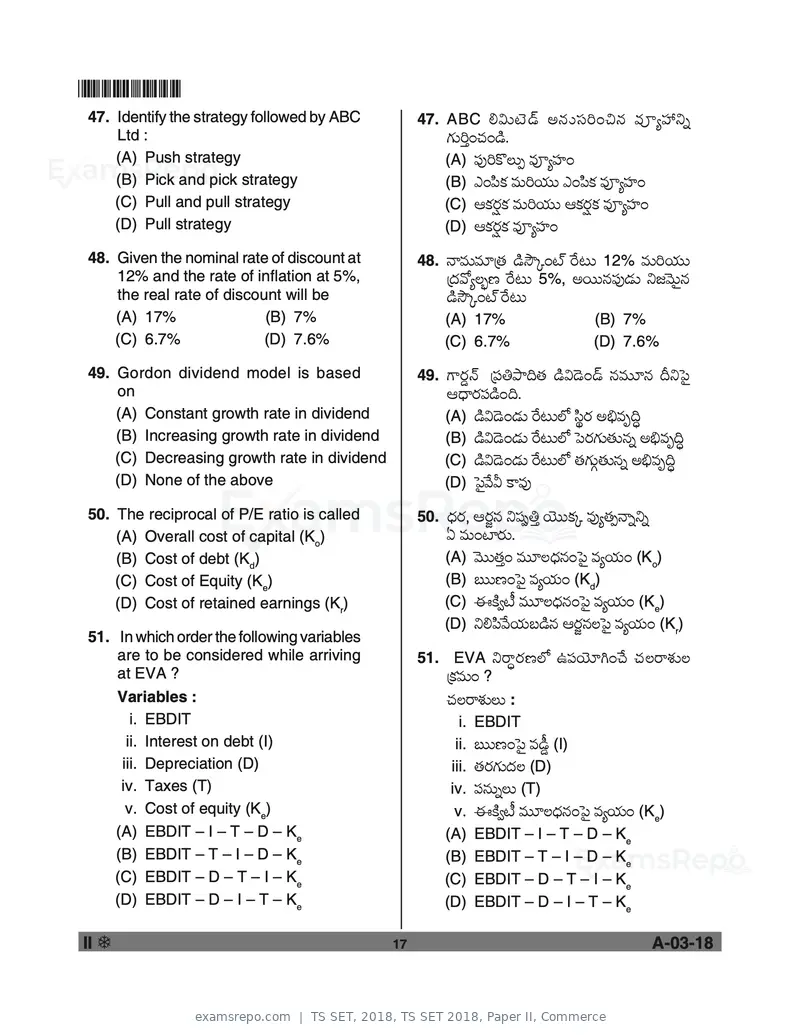
Text of page 17
*A0302*
47. Identify the strategy followed by ABC 47. ABC ÍÑ$sñ ý yŠ þ A¯è þ $ç Ü Ç…_¯è þ Ðè þ NÅà°²
Ltd : Væü$Ç¢…^èþ…yìþ.
(A) Push strategy (A) ç³#ÇMöË$µ ÐèþNÅçßý…
(B) Pick and pick strategy (B) G…í³Mæü Ðèþ$ÇÄæý$$ G…í³Mæü ÐèþNÅçßý…
(C) Pull and pull strategy (C) BMæüÆæÿÛMæü Ðèþ$ÇÄæý$$ BMæüÆæÿÛMæü ÐèþNÅçßý…
(D) Pull strategy (D) BMæüÆæÿÛMæü ÐèþNÅçßý…
48. Given the nominal rate of discount at 48. ¯éÐèþ$Ðèþ*{™èþ yìþÝûP…sŒý Æóÿr$ 12% Ðèþ$ÇÄæý$$
12% and the rate of inflation at 5%, {§æþÐøÅËÂ×ý Æóÿr$ 5%, AÆÿ$$¯èþç³#yæþ$ °fÐðþ$O¯èþ
the real rate of discount will be yìþÝûP…sŒý Æóÿr$
(A) 17% (B) 7% (A) 17% (B) 7%
(C) 6.7% (D) 7.6% (C) 6.7% (D) 7.6%
49. Gordon dividend model is based 49. V>Ææÿz¯Œþþ {糆´ë¨™èþ yìþÑyðþ…yŠþ ¯èþÐèþ$*¯èþ ©°ò³O
on B«§éÆæÿç³yìþ…¨.
(A) Constant growth rate in dividend (A) yìþÑyðþ…yæþ$ Æóÿr$ÌZ íܦÆæÿ AÀÐèþ–¨®
(B) Increasing growth rate in dividend (B) yìþÑyðþ…yæþ$ Æóÿr$ÌZ ò³ÆæÿVæü$™èþ$¯èþ² AÀÐèþ–¨®
(C) Decreasing growth rate in dividend (C) yìþÑyðþ…yæþ$ Æóÿr$ÌZ ™èþVæü$Y™èþ$¯èþ² AÀÐèþ–¨®
(D) None of the above (D) ò³OÐóþÒ M>Ðèþ#
50. The reciprocal of P/E ratio is called 50. «§æþÆæÿ, BÆæÿj¯èþ °çÙµ†¢ Äñý$$MæüP Ðèþ#Å™èþµ¯é²°²
(A) Overall cost of capital (Ko) H Ðèþ$…sêÆæÿ$.
(B) Cost of debt (Kd) (A) Ððþ$$™èþ¢… Ðèþ$*Ë«§æþ¯èþ…ò³O ÐèþÅÄæý$… (Ko)
(C) Cost of Equity (Ke) (B) º$$×ý…ò³O ÐèþÅÄæý$… (Kd)
(D) Cost of retained earnings (Kr) (C) DMìüÓsîý Ðèþ$*Ë«§æþ¯èþ…ò³O ÐèþÅÄæý$… (Ke)
(D) °Íí³ÐóþÄæý$ºyìþ¯èþ BÆæÿj¯èþËò³O ÐèþÅÄæý$… (Kr)
51. In which order the following variables
are to be considered while arriving 51. EVA °Æ>®Ææÿ×ýÌZ Eç³Äñý*W…^óþ ^èþËÆ>Ôèý$Ë
at EVA ? {MæüÐèþ$… ?
Variables : ^èþËÆ>Ôèý$Ë$ :
i. EBDIT i. EBDIT
ii. Interest on debt (I) ii. º$$×ý…ò³O Ðèþyîþz (I)
iii. Depreciation (D) iii. ™èþÆæÿVæü$§æþË (D)
iv. Taxes (T) iv. 糯èþ$²Ë$ (T)
v. Cost of equity (Ke) v. DMìüÓsîý Ðèþ$*Ë«§æþ¯èþ…ò³O ÐèþÅÄæý$… (Ke)
(A) EBDIT – I – T – D – Ke (A) EBDIT – I – T – D – Ke
(B) EBDIT – T – I – D – Ke (B) EBDIT – T – I – D – Ke
(C) EBDIT – D – T – I – Ke (C) EBDIT – D – T – I – Ke
(D) EBDIT – D – I – T – Ke (D) EBDIT – D – I – T – Ke
II 17 A-03-18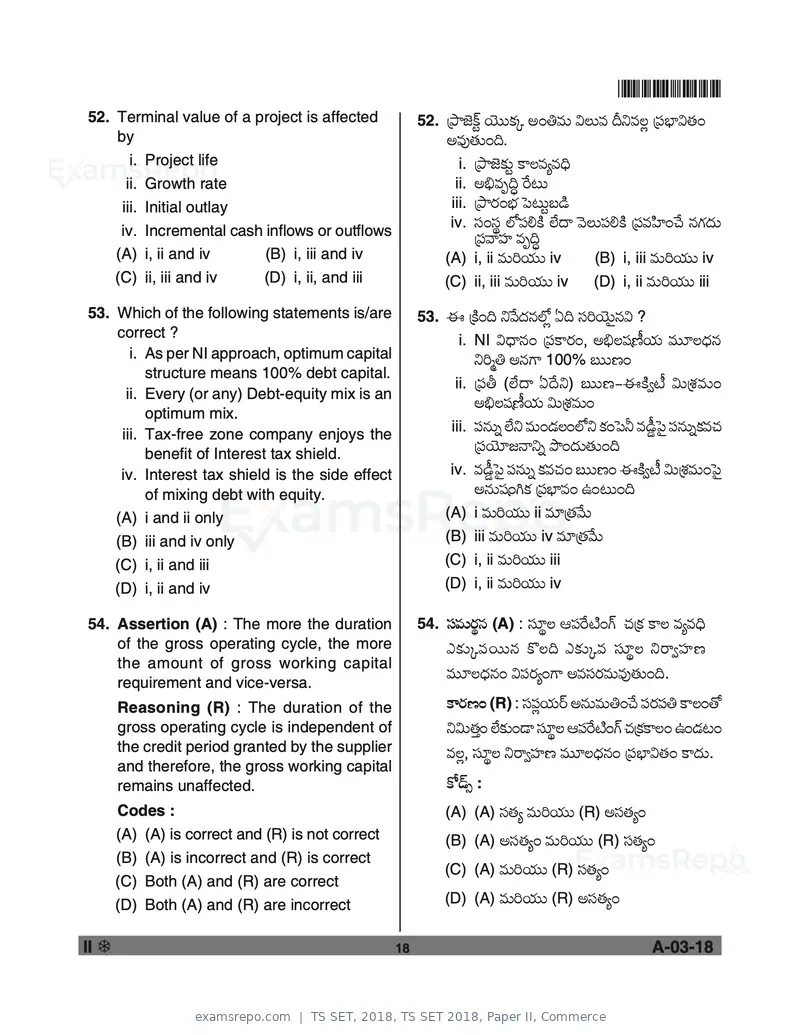
Text of page 18
*A0302*
52. Terminal value of a project is affected 52. {´ëgñýMŠüt Äñý$$MæüP A…†Ðèþ$ ÑË$Ðèþ ©°ÐèþËÏ {糿êÑ™èþ…
by AÐèþ#™èþ$…¨.
i. Project life i. {´ëgñýMæü$t M>ËÐèþÅÐèþ«¨
ii. Growth rate ii. AÀÐèþ–¨® Æóÿr$
iii. Initial outlay iii. {´ëÆæÿ…¿æý ò³r$tºyìþ
iv. çÜ…çܦ ÌZç³ÍMìü Ìôý§é ÐðþË$ç³ÍMìü {ç³Ðèþíßý…^óþ ¯èþVæü§æþ$
iv. Incremental cash inflows or outflows {ç³Ðéçßý Ðèþ–¨®
(A) i, ii and iv (B) i, iii and iv (A) i, ii Ðèþ$ÇÄæý$$ iv (B) i, iii Ðèþ$ÇÄæý$$ iv
(C) ii, iii and iv (D) i, ii, and iii (C) ii, iii Ðèþ$ÇÄæý$$ iv (D) i, ii Ðèþ$ÇÄæý$$ iii
53. Which of the following statements is/are 53. D {Mìü…¨ °Ðóþ§æþ¯èþÌZÏ H¨ çÜÇÄñý$O¯èþÑ ?
correct ? i. NI Ñ«§é¯èþ… {ç³M>Ææÿ…, AÀËçÙ×îýÄæý$ Ðèþ$*Ë«§æþ¯èþ
i. As per NI approach, optimum capital °ÇÆ A¯èþV> 100% º$$×ý…
structure means 100% debt capital.
ii. {糡 (Ìôý§é H§óþ°) º$$×ý&DMìüÓsîý Ñ${ÔèýÐèþ$…
ii. Every (or any) Debt-equity mix is an
AÀËçÙ×îýÄæý$ Ñ${ÔèýÐèþ$…
optimum mix.
iii. 糯èþ$² Ìôý° Ðèþ$…yæþË…ÌZ° Mæü…ò³± Ðèþyîþzò³O 糯èþ$²MæüÐèþ^èþ
iii. Tax-free zone company enjoys the
benefit of Interest tax shield.
{ç³Äñý*f¯é°² ´÷…§æþ$™èþ$…¨
iv. Interest tax shield is the side effect iv. Ðèþyîþzò³O 糯èþ$² MæüÐèþ^èþ… º$$×ý… DMìüÓsîý Ñ${ÔèýÐèþ$…ò³O
of mixing debt with equity. A¯èþ$çÙ…WMæü {糿êÐèþ… E…r$…¨
(A) i and ii only (A) i Ðèþ$ÇÄæý$$ ii Ðèþ*{™èþÐóþ$
(B) iii and iv only (B) iii Ðèþ$ÇÄæý$$ iv Ðèþ*{™èþÐóþ$
(C) i, ii and iii (C) i, ii Ðèþ$ÇÄæý$$ iii
(D) i, ii and iv (D) i, ii Ðèþ$ÇÄæý$$ iv
54. Assertion (A) : The more the duration 54. çÜÐèþ$Ææÿ¦¯èþ (A) : çÜ*¦Ë Bç³Æóÿsìý…VŠüü ^èþ{Mæü M>Ë ÐèþÅÐèþ«¨
of the gross operating cycle, the more GMæü$PÐèþÆÿ$$¯èþ Mö˨ GMæü$PÐèþ çÜ*¦Ë °Æ>Óçßý×ý
the amount of gross working capital
requirement and vice-versa.
Ðèþ$*Ë«§æþ¯èþ… Ñç³ÆæÿÅ…V> AÐèþçÜÆæÿÐèþ$Ðèþ#™èþ$…¨.
Reasoning (R) : The duration of the M>Ææÿ×ý… (R) : çÜç³ÏÄæý$ÆŠÿ A¯èþ$Ðèþ$†…^óþ ç³Ææÿ糆 M>Ë…™ø
gross operating cycle is independent of °Ñ$™èþ¢… ÌôýMæü$…yé çÜ*¦Ë Bç³Æóÿsìý…VŠü ^èþ{MæüM>Ë… E…yæþr…
the credit period granted by the supplier ÐèþËÏ, çÜ*¦Ë °Æ>Óçßý×ý Ðèþ$*Ë«§æþ¯èþ… {糿êÑ™èþ… M>§æþ$.
and therefore, the gross working capital
remains unaffected. MøyŠþÞ :
Codes : (A) (A) çÜ™èþÅ Ðèþ$ÇÄæý$$ (R) AçÜ™èþÅ…
(A) (A) is correct and (R) is not correct (B) (A) AçÜ™èþÅ… Ðèþ$ÇÄæý$$ (R) çÜ™èþÅ…
(B) (A) is incorrect and (R) is correct
(C) (A) Ðèþ$ÇÄæý$$ (R) çÜ™èþÅ…
(C) Both (A) and (R) are correct
(D) Both (A) and (R) are incorrect (D) (A) Ðèþ$ÇÄæý$$ (R) AçÜ™èþÅ…
II 18 A-03-18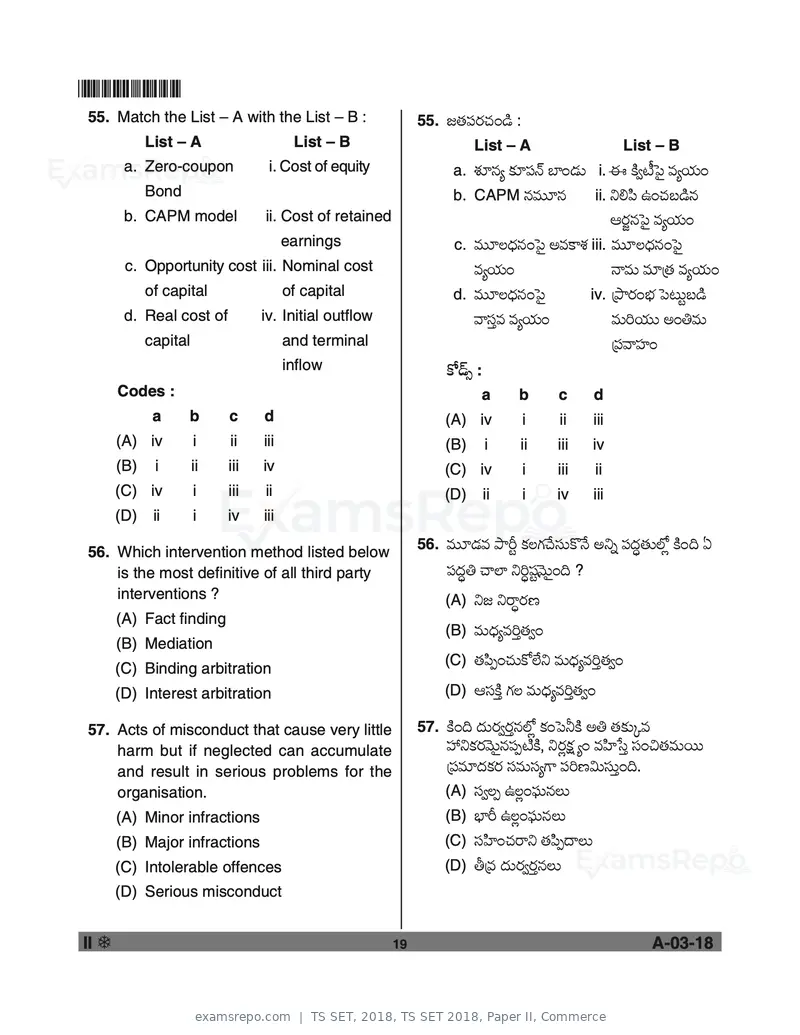
Text of page 19
*A0302*
55. Match the List – A with the List – B : 55. f™èþç³Ææÿ^èþ…yìþ :
List – A List – B List – A List – B
a. Zero-coupon i. Cost of equity a. Ôèý*¯èþÅ Mæü*糯Œþ »ê…yæþ$ i. D MìüÓsîýò³O ÐèþÅÄæý$…
Bond b. CAPM ¯èþÐèþ$*¯èþ ii. °Íí³ E…^èþºyìþ¯èþ
b. CAPM model ii. Cost of retained BÆæÿj¯èþò³O ÐèþÅÄæý$…
earnings c. Ðèþ$*Ë«§æþ¯èþ…ò³O AÐèþM>Ôèý iii. Ðèþ$*Ë«§æþ¯èþ…ò³O
c. Opportunity cost iii. Nominal cost ÐèþÅÄæý$… ¯éÐèþ$ Ðèþ*{™èþ ÐèþÅÄæý$…
of capital of capital d. Ðèþ$*Ë«§æþ¯èþ…ò³O iv. {´ëÆæÿ…¿æý ò³r$tºyìþ
d. Real cost of iv. Initial outflow ÐéçÜ¢Ðèþ ÐèþÅÄæý$… Ðèþ$ÇÄæý$$ A…†Ðèþ$
capital and terminal {ç³Ðéçßý…
inflow MøyŠþÞ :
Codes : a b c d
a b c d (A) iv i ii iii
(A) iv i ii iii (B) i ii iii iv
(B) i ii iii iv (C) iv i iii ii
(C) iv i iii ii (D) ii i iv iii
(D) ii i iv iii
56. Ðèþ$*yæþÐèþ ´ëÈt MæüËVæü^óþçÜ$Mö¯óþ A°² 糧æþ®™èþ$ÌZÏ Mìü…¨ H
56. Which intervention method listed below
is the most definitive of all third party 糧æþ®† ^éÌê °Ç®çÙtÐðþ$O…¨ ?
interventions ? (A) °f °Æ>®Ææÿ×ý
(A) Fact finding
(B) Ðèþ$«§æþÅÐèþÇ¢™èþÓ…
(B) Mediation
(C) ™èþí³µ…^èþ$MøÌôý° Ðèþ$«§æþÅÐèþÇ¢™èþÓ…
(C) Binding arbitration
(D) Interest arbitration (D) BçÜMìü¢ VæüË Ðèþ$«§æþÅÐèþÇ¢™èþÓ…
57. Acts of misconduct that cause very little 57. Mìü…¨ §æþ$ÆæÿÓÆæÿ¢¯èþÌZÏ Mæü…ò³±Mìü A† ™èþMæü$PÐèþ
harm but if neglected can accumulate à°MæüÆæÿÐðþ$O¯èþç³µsìýMìü, °ÆæÿÏ„æü Å… ÐèþíßýõÜ¢ çÜ…_™èþÐèþ$Æÿ$$
and result in serious problems for the {ç³Ðèþ*§æþMæüÆæÿ çÜÐèþ$çÜÅV> ç³Ç×ýÑ$çÜ$¢…¨.
organisation. (A) çÜÓ˵ EËÏ…çœ$¯èþË$
(A) Minor infractions (B) ¿êÈ EËÏ…çœ$¯èþË$
(B) Major infractions (C) çÜíßý…^èþÆ>° ™èþí³µ§éË$
(C) Intolerable offences (D) ¡{Ðèþ §æþ$ÆæÿÓÆæÿ¢¯èþË$
(D) Serious misconduct
II 19 A-03-18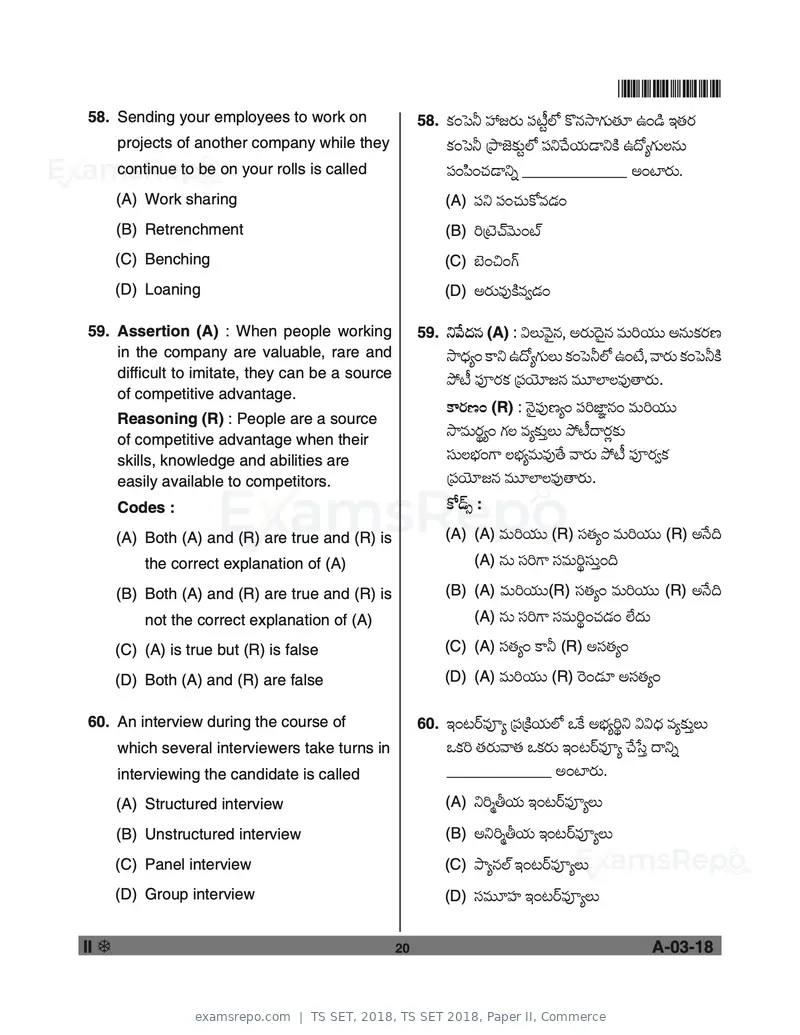
Text of page 20
*A0302*
58. Sending your employees to work on 58. Mæü…ò³± àfÆæÿ$ ç³sîýtÌZ Mö¯èþÝëVæü$™èþ* E…yìþ C™èþÆæÿ
projects of another company while they Mæü…ò³± {´ëgñýMæü$tÌZ ç³°^óþÄæý$yé°Mìü E§øÅVæü$˯èþ$
continue to be on your rolls is called ç³…í³…^èþyé°² ____________ A…sêÆæÿ$.
(A) Work sharing (A) ç³° ç³…^èþ$MøÐèþyæþ…
(B) Retrenchment (B) Ç{sñý^ŒþÐðþ$…sŒý
(C) Benching (C) »ñý…_…VŠü
(D) Loaning (D) AÆæÿ$Ðèþ#MìüÐèþÓyæþ…
59. Assertion (A) : When people working 59. °Ðóþ§æþ¯èþ (A) : ÑË$ÐðþO¯èþ, AÆæÿ$§ðþO¯èþ Ðèþ$ÇÄæý$$ A¯èþ$MæüÆæÿ×ý
in the company are valuable, rare and Ý뫧æþÅ… M>° E§øÅVæü$Ë$ Mæü…ò³±ÌZ E…sôý, ÐéÆæÿ$ Mæü…ò³±Mìü
difficult to imitate, they can be a source ´ùsîý ç³NÆæÿMæü {ç³Äñý*f¯èþ Ðèþ$*ÌêËÐèþ#™éÆæÿ$.
of competitive advantage.
M>Ææÿ×ý… (R) : ¯ðþOç³#×ýÅ… ç³Çgêq¯èþ… Ðèþ$ÇÄæý$$
Reasoning (R) : People are a source
of competitive advantage when their
ÝëÐèþ$Ææÿ¦Å… VæüË ÐèþÅMæü$¢Ë$ ´ùsîý§éÆæÿÏMæü$
skills, knowledge and abilities are çÜ$Ë¿æý…V> Ë¿æýÅÐèþ$Ðèþ#™óþ ÐéÆæÿ$ ´ùsîý ç³NÆæÿÓMæü
easily available to competitors. {ç³Äñý*f¯èþ Ðèþ$*ÌêËÐèþ#™éÆæÿ$.
Codes : MøyŠþÞ :
(A) Both (A) and (R) are true and (R) is (A) (A) Ðèþ$ÇÄæý$$ (R) çÜ™èþÅ… Ðèþ$ÇÄæý$$ (R) A¯óþ¨
the correct explanation of (A) (A) ¯èþ$ çÜÇV> çÜÐèþ$ǦçÜ$¢…¨
(B) Both (A) and (R) are true and (R) is (B) (A) Ðèþ$ÇÄæý$$(R) çÜ™èþÅ… Ðèþ$ÇÄæý$$ (R) A¯óþ¨
not the correct explanation of (A) (A) ¯èþ$ çÜÇV> çÜÐèþ$Ǧ…^èþyæþ… Ìôý§æþ$
(C) (A) is true but (R) is false (C) (A) çÜ™èþÅ… M>± (R) AçÜ™èþÅ…
(D) Both (A) and (R) are false (D) (A) Ðèþ$ÇÄæý$$ (R) Æðÿ…yæþ* AçÜ™èþÅ…
60. An interview during the course of 60. C…rÆŠÿÐèþNÅ {ç³{MìüÄæý$ÌZ JMóü A¿æýÅǦ° ÑÑ«§æþ ÐèþÅMæü$¢Ë$
which several interviewers take turns in JMæüÇ ™èþÆæÿ$Ðé™èþ JMæüÆæÿ$ C…rÆŠÿÐèþNÅ ^óþõÜ¢ §é°²
interviewing the candidate is called ____________ A…sêÆæÿ$.
(A) Structured interview (A) °ÇáÄæý$ C…rÆŠÿÐèþNÅË$
(B) Unstructured interview (B) A°ÇáÄæý$ C…rÆŠÿÐèþNÅË$
(C) Panel interview (C) ´ëůèþÌŒý C…rÆŠÿÐèþNÅË$
(D) Group interview (D) çÜÐèþ$*çßý C…rÆŠÿÐèþNÅË$
II 20 A-03-18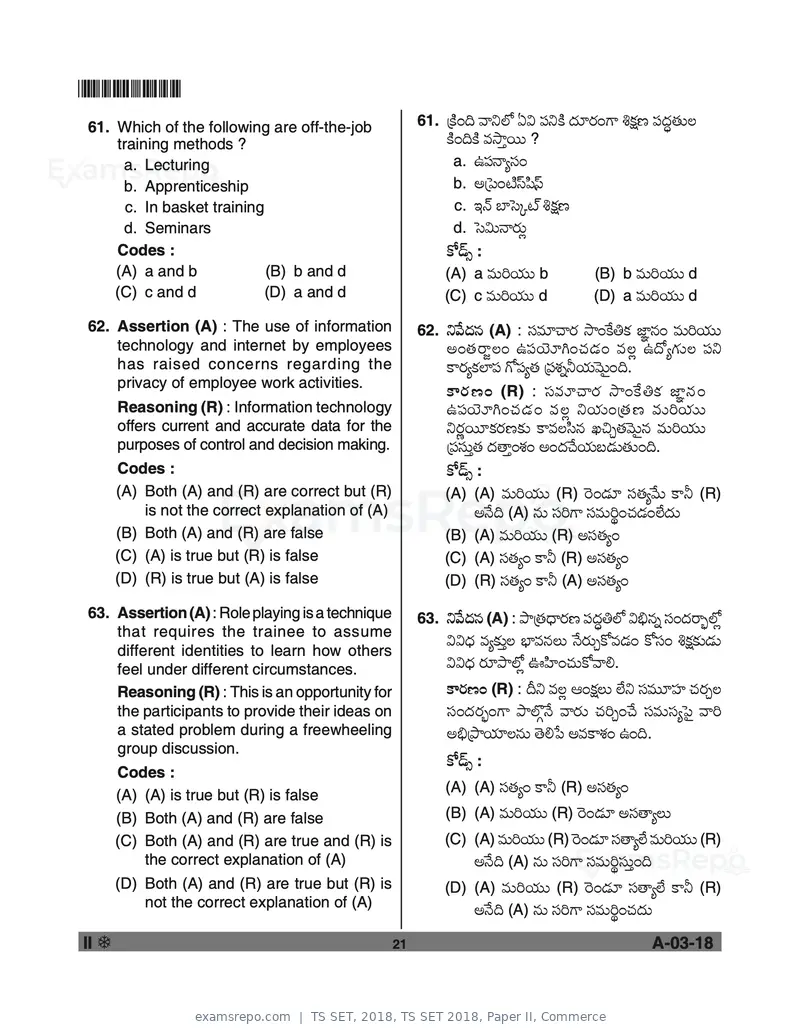
Text of page 21
*A0302*
61. Which of the following are off-the-job 61. {Mìü…¨ Ðé°ÌZ HÑ ç³°Mìü §æþ*Ææÿ…V> Õ„æü×ý 糧æþ®™èþ$Ë
training methods ? Mìü…¨Mìü ÐèþÝë¢Æÿ$$ ?
a. Lecturing a. E糯éÅçÜ…
b. Apprenticeship b. A{ò³…sìý‹ÜíÙ‹³
c. In basket training c. C¯Œþ »êòÜPsŒý Õ„æü×ý
d. Seminars d. òÜÑ$¯éÆæÿ$Ï
Codes : MøyŠþÞ :
(A) a and b (B) b and d (A) a Ðèþ$ÇÄæý$$ b (B) b Ðèþ$ÇÄæý$$ d
(C) c and d (D) a and d (C) c Ðèþ$ÇÄæý$$ d (D) a Ðèþ$ÇÄæý$$ d
62. Assertion (A) : The use of information 62. °Ðóþ§æþ¯èþ (A) : çÜÐèþ*^éÆæÿ Ýë…Móü†Mæü gêq¯èþ… Ðèþ$ÇÄæý$$
technology and internet by employees A…™èþÆ>jË… Eç³Äñý*W…^èþyæþ… ÐèþËÏ E§øÅVæü$Ë ç³°
has raised concerns regarding the M>ÆæÿÅMæüÌêç³ Vøç³Å™èþ {ç³Ôèý²±Äæý$Ððþ$O…¨.
privacy of employee work activities.
M>Ææ ÿ ×ý… (R) : ç Ü Ðè þ *^éÆæ ÿ Ýë…Mó ü †Mæ ü gêq ¯ è þ …
Reasoning (R) : Information technology Eç³Äñý*W…^èþyæþ… ÐèþËÏ °Äæý$…{™èþ×ý Ðèþ$ÇÄæý$$
offers current and accurate data for the °Ææÿ~Æÿ$*MæüÆæÿ×ýMæü$ M>ÐèþËíܯèþ Q_a™èþÐðþ$O¯èþ Ðèþ$ÇÄæý$$
purposes of control and decision making. {ç³çÜ$¢™èþ §æþ™é¢…Ôèý… A…§æþ^óþÄæý$ºyæþ$™èþ$…¨.
Codes : MøyŠþÞ :
(A) Both (A) and (R) are correct but (R) (A) (A) Ðèþ$ÇÄæý$$ (R) Æðÿ…yæþ* çÜ™èþÅÐóþ$ M>± (R)
is not the correct explanation of (A) A¯óþ¨ (A) ¯èþ$ çÜÇV> çÜÐèþ$Ǧ…^èþyæþ…Ìôý§æþ$
(B) Both (A) and (R) are false (B) (A) Ðèþ$ÇÄæý$$ (R) AçÜ™èþÅ…
(C) (A) is true but (R) is false (C) (A) çÜ™èþÅ… M>± (R) AçÜ™èþÅ…
(D) (R) is true but (A) is false (D) (R) çÜ™èþÅ… M>± (A) AçÜ™èþÅ…
63. Assertion (A) : Role playing is a technique 63. °Ðóþ§æþ¯èþ (A) : ´ë{™èþ«§éÆæÿ×ý 糧æþ®†ÌZ ÑÀ¯èþ² çÜ…§æþÆ>ÂÌZÏ
that requires the trainee to assume
different identities to learn how others
ÑÑ«§æþ ÐèþÅMæü$¢Ë ¿êÐèþ¯èþË$ ¯óþÆæÿ$aMøÐèþyæþ… MøçÜ… Õ„æüMæü$yæþ$
feel under different circumstances. ÑÑ«§æþ Ææÿ*´ëÌZÏ Fíßý…^èþ$MøÐéÍ.
Reasoning (R) : This is an opportunity for M>Ææÿ×ý… (R) : ©° ÐèþËÏ B…„æüË$ Ìôý° çÜÐèþ$*çßý ^èþÆæÿaË
the participants to provide their ideas on çÜ…§æþÆæÿÂ…V> ´ëÌŸY¯óþ ÐéÆæÿ$ ^èþÇa…^óþ çÜÐèþ$çÜÅò³O ÐéÇ
a stated problem during a freewheeling AÀ{´ëÄæý*˯èþ$ ™ðþÍõ³ AÐèþM>Ôèý… E…¨.
group discussion.
MøyŠþÞ :
Codes :
(A) (A) çÜ™èþÅ… M>± (R) AçÜ™èþÅ…
(A) (A) is true but (R) is false
(B) Both (A) and (R) are false (B) (A) Ðèþ$ÇÄæý$$ (R) Æðÿ…yæþ* AçÜ™éÅË$
(C) Both (A) and (R) are true and (R) is (C) (A) Ðèþ$ÇÄæý$$ (R) Æðÿ…yæþ* çÜ™éÅÌôý Ðèþ$ÇÄæý$$ (R)
the correct explanation of (A) A¯óþ¨ (A) ¯èþ$ çÜÇV> çÜÐèþ$ǦçÜ$¢…¨
(D) Both (A) and (R) are true but (R) is (D) (A) Ðèþ$ÇÄæý$$ (R) Æðÿ…yæþ* çÜ™éÅÌôý M>± (R)
not the correct explanation of (A) A¯óþ¨ (A) ¯èþ$ çÜÇV> çÜÐèþ$Ǧ…^èþ§æþ$
II 21 A-03-18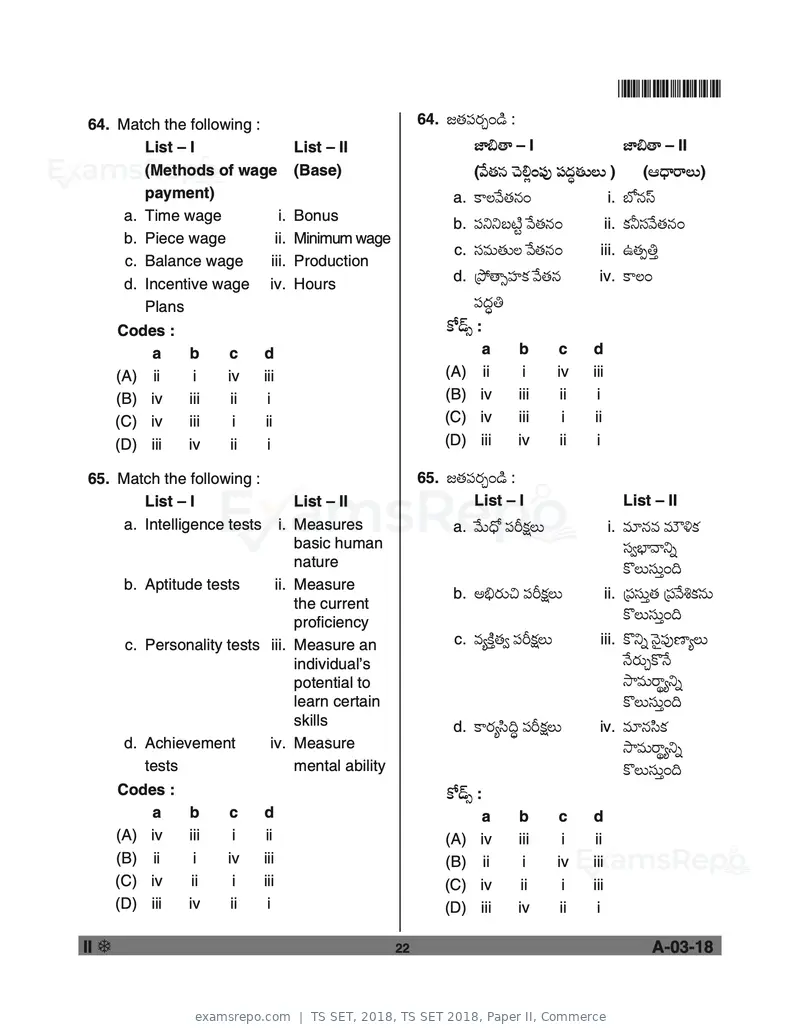
Text of page 22
*A0302*
64. Match the following : 64. f™èþç³Ææÿa…yìþ :
List – I List – II gê¼™é – I gê¼™é – II
(Methods of wage (Base) (Ðóþ™èþ¯èþ ^ðþÍÏ…ç³# 糧æþ®™èþ$Ë$ ) (B«§éÆ>Ë$)
payment) a. M>ËÐóþ™èþ¯èþ… i. »Z¯èþ‹Ü
a. Time wage i. Bonus
b. ç³°°ºsìýt Ðóþ™èþ¯èþ… ii. Mæü±çÜÐóþ™èþ¯èþ…
b. Piece wage ii. Minimum wage
c. çÜÐèþ$™èþ$Ë Ðóþ™èþ¯èþ… iii. E™èþµ†¢
c. Balance wage iii. Production
d. {´ù™éÞçßýMæü Ðóþ™èþ¯èþ iv. M>Ë…
d. Incentive wage iv. Hours
Plans 糧æþ®†
Codes : MøyŠþÞ :
a b c d a b c d
(A) ii i iv iii (A) ii i iv iii
(B) iv iii ii i (B) iv iii ii i
(C) iv iii i ii (C) iv iii i ii
(D) iii iv ii i (D) iii iv ii i
65. Match the following : 65. f™èþç³Ææÿa…yìþ :
List – I List – II List – I List – II
a. Intelligence tests i. Measures a. Ðóþ$«§ø ç³È„æüË$ i. Ðèþ*¯èþÐèþ Ðèþ˜ãMæü
basic human çÜÓ¿êÐé°²
nature MöË$çÜ$¢…¨
b. Aptitude tests ii. Measure
b. AÀÆæÿ$_ ç³È„æüË$ ii. {ç³çÜ$¢™èþ {ç³ÐóþÕMæü¯èþ$
the current
proficiency
MöË$çÜ$¢…¨
c. Personality tests iii. Measure an c. ÐèþÅMìü¢™èþÓ ç³È„æüË$ iii. Mö°² ¯ðþOç³#×êÅË$
individual’s ¯óþÆæÿ$aMö¯óþ
potential to ÝëÐèþ$Æ>¦Å°²
learn certain MöË$çÜ$¢…¨
skills d. M>ÆæÿÅíܨ® ç³È„æüË$ iv. Ðèþ*¯èþíÜMæü
d. Achievement iv. Measure ÝëÐèþ$Æ>¦Å°²
tests mental ability MöË$çÜ$¢…¨
Codes : MøyŠþÞ :
a b c d a b c d
(A) iv iii i ii (A) iv iii i ii
(B) ii i iv iii (B) ii i iv iii
(C) iv ii i iii (C) iv ii i iii
(D) iii iv ii i (D) iii iv ii i
II 22 A-03-18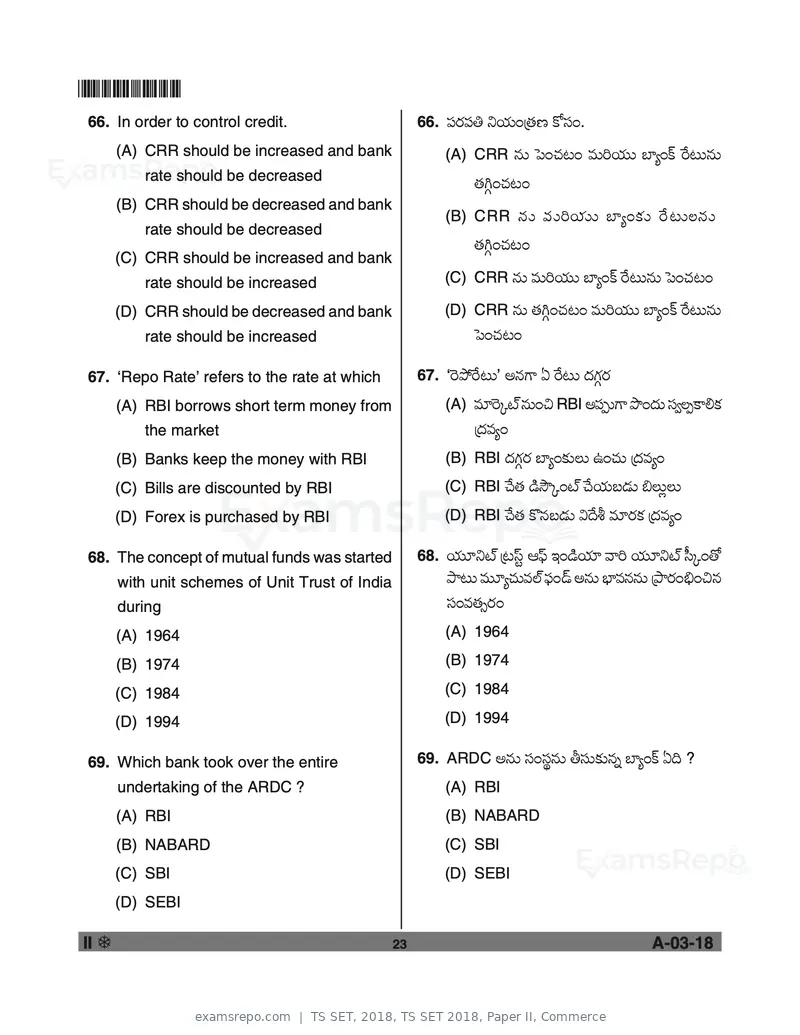
Text of page 23
*A0302*
66. In order to control credit. 66. ç³Ææÿ糆 °Äæý$…{™èþ×ý MøçÜ….
(A) CRR should be increased and bank (A) CRR ¯èþ$ ò³…^èþr… Ðèþ$ÇÄæý$$ »êÅ…MŠü Æóÿr$¯èþ$
rate should be decreased ™èþWY…^èþr…
(B) CRR should be decreased and bank
(B) CRR ¯è þ $ Ðè þ $ÇÄæ ý $$ »êÅ…Mæ ü $ Æó ÿ r$˯è þ $
rate should be decreased
™èþWY…^èþr…
(C) CRR should be increased and bank
rate should be increased (C) CRR ¯èþ$ Ðèþ$ÇÄæý$$ »êÅ…MŠü Æóÿr$¯èþ$ ò³…^èþr…
(D) CRR should be decreased and bank (D) CRR ¯èþ$ ™èþWY…^èþr… Ðèþ$ÇÄæý$$ »êÅ…MŠü Æóÿr$¯èþ$
rate should be increased ò³…^èþr…
67. ‘Repo Rate’ refers to the rate at which 67. ‘Æðÿ´ùÆóÿr$’ A¯èþV> H Æóÿr$ §æþVæüYÆæÿ
(A) RBI borrows short term money from (A) Ðèþ*ÆðÿPsŒý ¯èþ$…_ RBI A糚V> ´÷…§æþ$ çÜÓ˵M>ÍMæü
the market {§æþÐèþÅ…
(B) Banks keep the money with RBI (B) RBI §æþVæüYÆæÿ »êÅ…Mæü$Ë$ E…^èþ$ {§æþÐèþÅ…
(C) Bills are discounted by RBI (C) RBI ^óþ™èþ yìþÝûP…sŒý ^óþÄæý$ºyæþ$ ¼Ë$ÏË$
(D) Forex is purchased by RBI (D) RBI ^óþ™èþ Mö¯èþºyæþ$ ѧóþÖ Ðèþ*ÆæÿMæü {§æþÐèþÅ…
68. The concept of mutual funds was started 68. Äæý$*°sŒý {r‹Üt B‹œ C…yìþÄæý* ÐéÇ Äæý$*°sŒý ïÜP…™ø
with unit schemes of Unit Trust of India ´ër$ Ðèþ$*Å^èþ$ÐèþÌŒý 眅yŠþ A¯èþ$ ¿êÐèþ¯èþ¯èþ$ {´ëÆæÿ…À…_¯èþ
during çÜ…Ðèþ™èþÞÆæÿ…
(A) 1964 (A) 1964
(B) 1974 (B) 1974
(C) 1984 (C) 1984
(D) 1994 (D) 1994
69. Which bank took over the entire 69. ARDC A¯èþ$ çÜ…çܦ¯èþ$ ¡çÜ$Mæü$¯èþ² »êÅ…MŠü H¨ ?
undertaking of the ARDC ? (A) RBI
(A) RBI (B) NABARD
(B) NABARD (C) SBI
(C) SBI (D) SEBI
(D) SEBI
II 23 A-03-18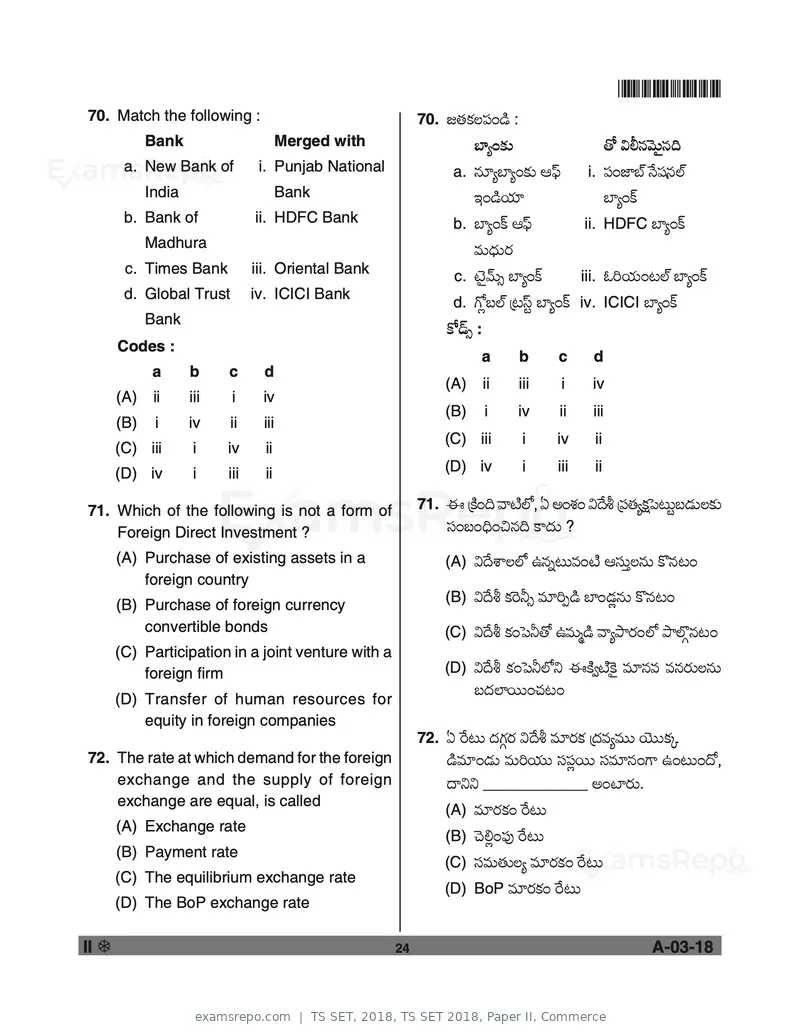
Text of page 24
*A0302*
70. Match the following : 70. f™èþMæüËç³…yìþ :
Bank Merged with »êÅ…Mæü$ ™ø ÑίèþÐðþ$O¯èþ¨
a. New Bank of i. Punjab National a. ¯èþ*Å»êÅ…Mæü$ B‹œ i. ç³…g껌ý ¯óþçÙ¯èþÌŒý
India Bank C…yìþÄæý* »êÅ…MŠü
b. Bank of ii. HDFC Bank b. »êÅ…MŠü B‹œ ii. HDFC »êÅ…MŠü
Madhura Ðèþ$«§æþ$Ææÿ
c. Times Bank iii. Oriental Bank c. sñýOÐŒþ$Þ »êÅ…MŠü iii. KÇÄæý$…rÌŒý »êÅ…MŠü
d. Global Trust iv. ICICI Bank
d. VøϺ̌ý {r‹Üt »êÅ…MŠü iv. ICICI »êÅ…MŠü
Bank
MøyŠþÞ :
Codes :
a b c d
a b c d
(A) ii iii i iv
(A) ii iii i iv
(B) i iv ii iii
(B) i iv ii iii
(C) iii i iv ii
(C) iii i iv ii
(D) iv i iii ii (D) iv i iii ii
71. Which of the following is not a form of 71. D {Mìü…¨ ÐésìýÌZ, H A…Ôèý… ѧóþÖ {ç³™èþÅ„æüò³r$tºyæþ$ËMæü$
Foreign Direct Investment ? çÜ…º…«¨…_¯èþ¨ M>§æþ$ ?
(A) Purchase of existing assets in a (A) ѧóþÔ>ËÌZ E¯èþ²r$Ðèþ…sìý BçÜ$¢Ë¯èþ$ Mö¯èþr…
foreign country
(B) ѧóþÖ MæüÆðÿ±Þ Ðèþ*ǵyìþ »ê…yæþϯèþ$ Mö¯èþr…
(B) Purchase of foreign currency
convertible bonds (C) ѧóþÖ Mæü…ò³±™ø EÐèþ$Ãyìþ ÐéÅ´ëÆæÿ…ÌZ ´ëÌŸY¯èþr…
(C) Participation in a joint venture with a
foreign firm (D) ѧóþÖ Mæü…ò³±ÌZ° DMìüÓsìýMðüO Ðèþ*¯èþÐèþ Ðèþ¯èþÆæÿ$˯èþ$
(D) Transfer of human resources for
º§æþÌêÆÿ$$…^èþr…
equity in foreign companies
72. H Æóÿr$ §æþVæüYÆæÿ ѧóþÖ Ðèþ*ÆæÿMæü {§æþÐèþÅÐèþ$$ Äñý$$MæüP
72. The rate at which demand for the foreign yìþÐèþ*…yæþ$ Ðèþ$ÇÄæý$$ çÜç³ÏÆÿ$$ çÜÐèþ*¯èþ…V> E…r$…§ø,
exchange and the supply of foreign §é°° ____________ A…sêÆæÿ$.
exchange are equal, is called
(A) Ðèþ*ÆæÿMæü… Æóÿr$
(A) Exchange rate
(B) ^ðþÍÏ…ç³# Æóÿr$
(B) Payment rate
(C) çÜÐèþ$™èþ$ËÅ Ðèþ*ÆæÿMæü… Æóÿr$
(C) The equilibrium exchange rate
(D) BoP Ðèþ*ÆæÿMæü… Æóÿr$
(D) The BoP exchange rate
II 24 A-03-18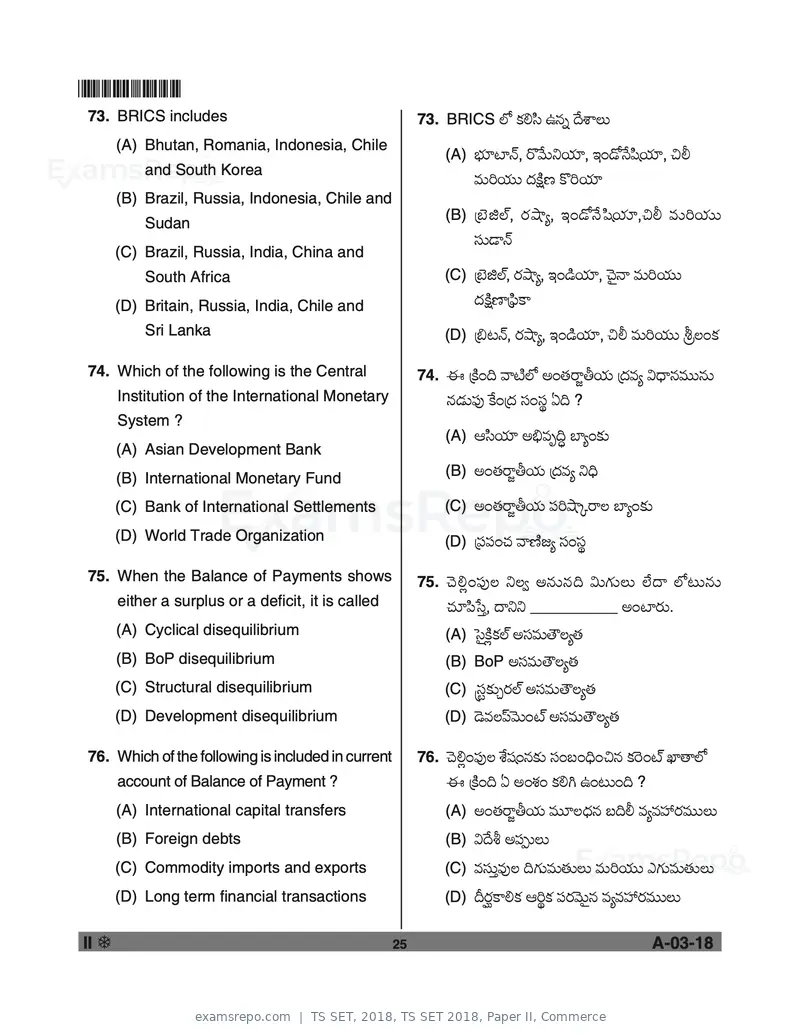
Text of page 25
*A0302*
73. BRICS includes 73. BRICS ÌZ MæüÍíÜ E¯èþ² §óþÔ>Ë$
(A) Bhutan, Romania, Indonesia, Chile
(A) ¿æý*sꯌþ, ÆöÐóþ$°Äæý*, C…yø¯óþíÙÄæý*, _Î
and South Korea
Ðèþ$ÇÄæý$$ §æþ„ìü×ý MöÇÄæý*
(B) Brazil, Russia, Indonesia, Chile and
(B) {»ñ ý hÌŒ ý , Ææ ÿ ÚëÅ, C…yø¯ó þ í Ù Äæ ý *,_Î Ðè þ $ÇÄæ ý $$
Sudan
çÜ$y鯌þ
(C) Brazil, Russia, India, China and
South Africa (C) {»ñýhÌŒý, ÆæÿÚëÅ, C…yìþÄæý*, ^ðþO¯é Ðèþ$ÇÄæý$$
(D) Britain, Russia, India, Chile and §æþ„ìü×ê{íœM>
Sri Lanka (D) {¼r¯Œþ, ÆæÿÚëÅ, C…yìþÄæý*, _Î Ðèþ$ÇÄæý$$ }Ë…Mæü
74. Which of the following is the Central 74. D {Mìü…¨ ÐésìýÌZ A…™èþÆ>j¡Äæý$ {§æþÐèþÅ Ñ«§é¯èþÐèþ$$¯èþ$
Institution of the International Monetary ¯èþyæþ$ç³# Móü…{§æþ çÜ…çܦ H¨ ?
System ?
(A) BíÜÄæý* AÀÐèþ–¨® »êÅ…Mæü$
(A) Asian Development Bank
(B) International Monetary Fund (B) A…™èþÆ>j¡Äæý$ {§æþÐèþÅ °«¨
(C) Bank of International Settlements (C) A…™èþÆ>j¡Äæý$ ç³ÇÚëPÆ>Ë »êÅ…Mæü$
(D) World Trade Organization (D) {ç³ç³…^èþ Ðé×ìýfÅ çÜ…çܦ
75. When the Balance of Payments shows 75. ^ðþÍÏ…ç³#Ë °ËÓ A¯èþ$¯èþ¨ Ñ$Væü$Ë$ Ìôý§é ÌZr$¯èþ$
either a surplus or a deficit, it is called ^èþ*í³õÜ¢, §é°° __________ A…sêÆæÿ$.
(A) Cyclical disequilibrium (A) òÜOMìüÏMæüÌŒý AçÜÐèþ$™úËÅ™èþ
(B) BoP disequilibrium (B) BoP AçÜÐèþ$™úËÅ™èþ
(C) Structural disequilibrium (C) [çÜtMæü$aÆæÿÌŒý AçÜÐèþ$™úËÅ™èþ
(D) Development disequilibrium (D) yðþÐèþË‹³Ððþ$…sŒý AçÜÐèþ$™úËÅ™èþ
76. Which of the following is included in current 76. ^ðþÍÏ…ç³#Ë ÔóýçÙ…¯èþMæü$ çÜ…º…«¨…_¯èþ MæüÆðÿ…sŒý Rê™éÌZ
account of Balance of Payment ? D {Mìü…¨ H A…Ôèý… MæüÍW E…r$…¨ ?
(A) International capital transfers (A) A…™èþÆ>j¡Äæý$ Ðèþ$*Ë«§æþ¯èþ º¨Î ÐèþÅÐèþàÆæÿÐèþ$$Ë$
(B) Foreign debts (B) ѧóþÖ A糚Ë$
(C) Commodity imports and exports (C) ÐèþçÜ$¢Ðèþ#Ë ¨Væü$Ðèþ$™èþ$Ë$ Ðèþ$ÇÄæý$$ GVæü$Ðèþ$™èþ$Ë$
(D) Long term financial transactions (D) ©ÆæÿƒM>ÍMæü BǦMæü ç³ÆæÿÐðþ$O¯èþ ÐèþÅÐèþàÆæÿÐèþ$$Ë$
II 25 A-03-18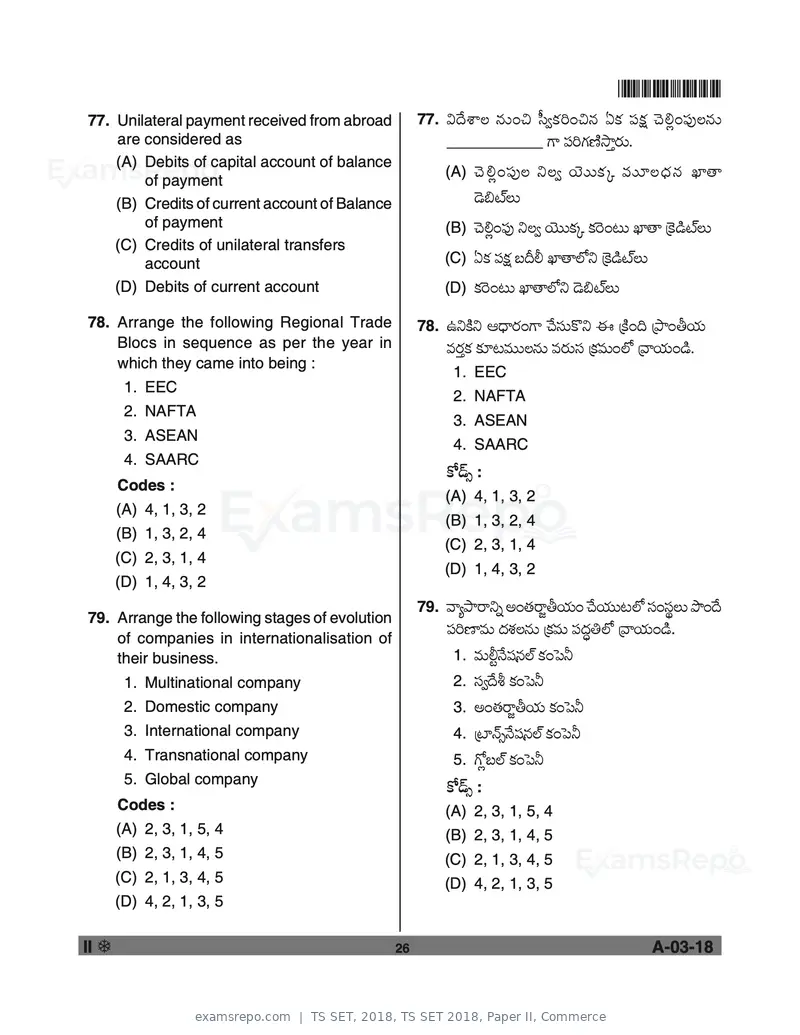
Text of page 26
*A0302*
77. Unilateral payment received from abroad 77. ѧóþÔ>Ë ¯èþ$…_ ïÜÓMæüÇ…_¯èþ HMæü 糄æü ^ðþÍÏ…ç³#˯èþ$
are considered as ___________ V> ç³ÇVæü×ìýÝë¢Ææÿ$.
(A) Debits of capital account of balance
(A) ^ð þ ÍÏ … ç ³ #Ë °ËÓ Äñ ý $$Mæ ü P Ðè þ $*Ë« § æ þ ¯è þ Rê™é
of payment
(B) Credits of current account of Balance yðþ¼sŒýË$
of payment (B) ^ðþÍÏ…ç³# °ËÓ Äñý$$MæüP MæüÆðÿ…r$ Rê™é {MðüyìþsŒýË$
(C) Credits of unilateral transfers
account (C) HMæü 糄æü º©Î Rê™éÌZ° {MðüyìþsŒýË$
(D) Debits of current account (D) MæüÆðÿ…r$ Rê™éÌZ° yðþ¼sŒýË$
78. Arrange the following Regional Trade 78. E°Mìü° B«§éÆæÿ…V> ^óþçÜ$Mö° D {Mìü…¨ {´ë…¡Äæý$
Blocs in sequence as per the year in ÐèþÆæÿ¢Mæü Mæü*rÐèþ$$˯èþ$ ÐèþÆæÿ$çÜ {MæüÐèþ$…ÌZ {ÐéÄæý$…yìþ.
which they came into being :
1. EEC
1. EEC
2. NAFTA
2. NAFTA
3. ASEAN
3. ASEAN
4. SAARC
4. SAARC
MøyŠþÞ :
Codes :
(A) 4, 1, 3, 2
(A) 4, 1, 3, 2
(B) 1, 3, 2, 4
(B) 1, 3, 2, 4
(C) 2, 3, 1, 4
(C) 2, 3, 1, 4
(D) 1, 4, 3, 2
(D) 1, 4, 3, 2
79. ÐéÅ´ëÆ>°² A…™èþÆ>j¡Äæý$… ^óþÄæý$$rÌZ çÜ…çܦË$ ´÷…§óþ
79. Arrange the following stages of evolution
of companies in internationalisation of
ç³Ç×êÐèþ$ §æþÔèý˯èþ$ {MæüÐèþ$ 糧æþ®†ÌZ {ÐéÄæý$…yìþ.
their business. 1. Ðèþ$Ît¯óþçÙ¯èþÌŒý Mæü…ò³±
1. Multinational company 2. çÜÓ§óþÖ Mæü…ò³±
2. Domestic company 3. A…™èþÆ>j¡Äæý$ Mæü…ò³±
3. International company 4. {sꯌþÞ¯óþçÙ¯èþÌŒý Mæü…ò³±
4. Transnational company 5. VøϺ̌ý Mæü…ò³±
5. Global company MøyŠþÞ :
Codes : (A) 2, 3, 1, 5, 4
(A) 2, 3, 1, 5, 4 (B) 2, 3, 1, 4, 5
(B) 2, 3, 1, 4, 5 (C) 2, 1, 3, 4, 5
(C) 2, 1, 3, 4, 5 (D) 4, 2, 1, 3, 5
(D) 4, 2, 1, 3, 5
II 26 A-03-18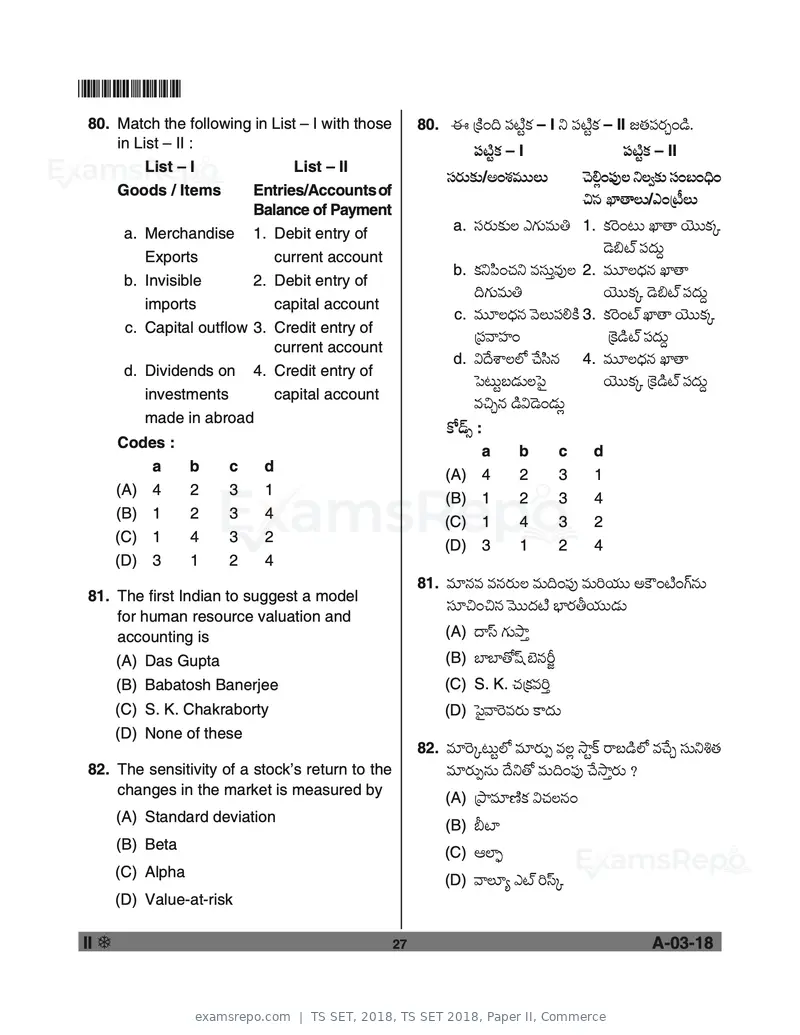
Text of page 27
*A0302*
80. Match the following in List – I with those 80.D {Mìü…¨ ç³sìýtMæü – I ° ç³sìýtMæü – II f™èþç³Ææÿa…yìþ.
in List – II : ç³sìýtMæü – I ç³sìýtMæü – II
List – I List – II
çÜÆæÿ$Mæü$/A…ÔèýÐèþ$$Ë$ ^ðþÍÏ…ç³#Ë °ËÓMæü$ çÜ…º…«¨…
Goods / Items Entries/Accounts of
_¯èþ Rê™éË$/G…{sîýË$
Balance of Payment
a. çÜÆæÿ$Mæü$Ë GVæü$Ðèþ$† 1. MæüÆðÿ…r$ Rê™é Äñý$$MæüP
a. Merchandise 1. Debit entry of
yðþ¼sŒý 糧æþ$ª
Exports current account
b. Mæü°í³…^èþ° ÐèþçÜ$¢Ðèþ#Ë 2. Ðèþ$*Ë«§æþ¯èþ Rê™é
b. Invisible 2. Debit entry of
¨Væü$Ðèþ$† Äñý$$MæüP yðþ¼sŒý 糧æþ$ª
imports capital account
c. Ðèþ$*Ë«§æþ¯èþ ÐðþË$ç³ÍMìü 3. MæüÆðÿ…sŒý Rê™é Äñý$$MæüP
c. Capital outflow 3. Credit entry of
{ç³Ðéçßý… {MðüyìþsŒý 糧æþ$ª
current account
d. ѧóþÔ>ËÌZ ^óþíܯèþ 4. Ðèþ$*Ë«§æþ¯èþ Rê™é
d. Dividends on 4. Credit entry of
ò³r$tºyæþ$Ëò³O Äñý$$MæüP {MðüyìþsŒý 糧æþ$ª
investments capital account
Ðèþ_a¯èþ yìþÑyðþ…yæþ$Ï
made in abroad
MøyŠþÞ :
Codes :
a b c d
a b c d
(A) 4 2 3 1
(A) 4 2 3 1
(B) 1 2 3 4
(B) 1 2 3 4
(C) 1 4 3 2
(C) 1 4 3 2
(D) 3 1 2 4
(D) 3 1 2 4
81. Ðèþ*¯èþÐèþ Ðèþ¯èþÆæÿ$Ë Ðèþ$¨…ç³# Ðèþ$ÇÄæý$$ AMú…sìý…VŠü¯èþ$
81. The first Indian to suggest a model
çÜ*_…_¯èþ Ððþ$$§æþsìý ¿êÆæÿ¡Äæý$$yæþ$
for human resource valuation and
accounting is (A) §é‹Ü Væü$´ë¢
(A) Das Gupta (B) »ê»ê™ø‹Ù »ñý¯èþÈj
(B) Babatosh Banerjee (C) S. K. ^èþ{MæüÐèþÇ¢
(C) S. K. Chakraborty (D) ò³OÐéÆðÿÐèþÆæÿ$ M>§æþ$
(D) None of these
82. Ðèþ*ÆðÿPr$tÌZ Ðèþ*Ææÿ$µ ÐèþËÏ ÝëtMŠü Æ>ºyìþÌZ Ðèþ^óþa çÜ$°Õ™èþ
82. The sensitivity of a stock’s return to the Ðèþ*Ææÿ$µ¯èþ$ §óþ°™ø Ðèþ$¨…ç³# ^óþÝë¢Ææÿ$ ?
changes in the market is measured by
(A) {´ëÐèþ*×ìýMæü Ñ^èþ˯èþ…
(A) Standard deviation
(B) ½sê
(B) Beta
(C) BÌê¹
(C) Alpha
(D) ÐéË*Å GsŒý Ç‹ÜP
(D) Value-at-risk
II 27 A-03-18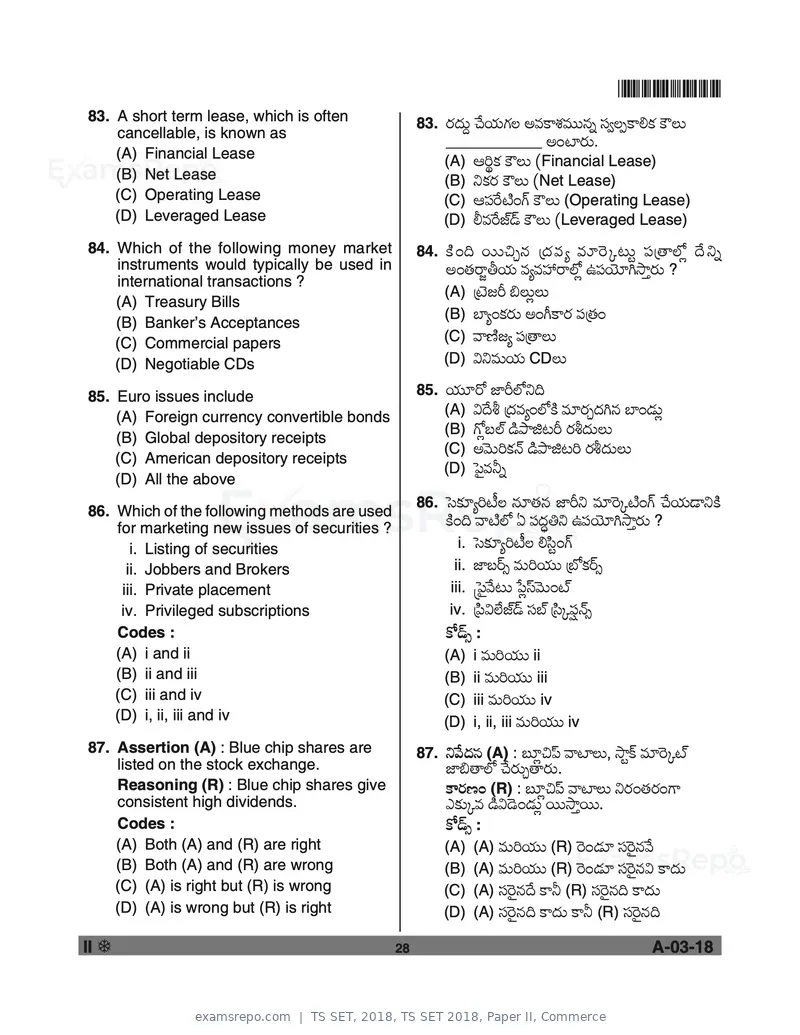
Text of page 28
*A0302*
83. A short term lease, which is often 83. Ææÿ§æþ$ª ^óþÄæý$VæüË AÐèþM>ÔèýÐèþ$$¯èþ² çÜÓ˵M>ÍMæü MúË$
cancellable, is known as
___________ A…sêÆæÿ$.
(A) Financial Lease (A) BǦMæü MúË$ (Financial Lease)
(B) Net Lease (B) °MæüÆæÿ MúË$ (Net Lease)
(C) Operating Lease (C) Bç³Æóÿsìý…VŠü MúË$ (Operating Lease)
(D) Leveraged Lease (D) ÎÐèþÆóÿgŒýyŠþ MúË$ (Leveraged Lease)
84. Which of the following money market 84. Mì ü …¨ Æÿ$$_a¯è þ {§æ þ Ðè þ Å Ðè þ *Æð ÿ Pr$t ç ³ {™éÌZÏ §ó þ °²
instruments would typically be used in A…™èþÆ>j¡Äæý$ ÐèþÅÐèþàÆ>ÌZÏ Eç³Äñý*WÝë¢Ææÿ$ ?
international transactions ?
(A) {sñýfÈ ¼Ë$ÏË$
(A) Treasury Bills
(B) »êÅ…MæüÆæÿ$ A…XM>Ææÿ ç³{™èþ…
(B) Banker’s Acceptances
(C) Commercial papers (C) Ðé×ìýfÅ ç³{™éË$
(D) Negotiable CDs (D) Ñ°Ðèþ$Äæý$ CDË$
85. Euro issues include 85. Äæý$*Æø gêÈÌZ°¨
(A) Foreign currency convertible bonds (A) ѧóþÖ {§æþÐèþÅ…ÌZMìü Ðèþ*Ææÿa§æþW¯èþ »ê…yæþ$Ï
(B) VøϺ̌ý yìþ´ëhrÈ ÆæÿÖ§æþ$Ë$
(B) Global depository receipts
(C) AÐðþ$ÇMæü¯Œþ yìþ´ëhrÇ ÆæÿÖ§æþ$Ë$
(C) American depository receipts
(D) ò³OÐèþ±²
(D) All the above
86. òÜMæü*ÅÇsîýË ¯èþ*™èþ¯èþ gêÈ° Ðèþ*ÆðÿPsìý…VŠü ^óþÄæý$yé°Mìü
86. Which of the following methods are used
for marketing new issues of securities ? Mìü…¨ ÐésìýÌZ H 糧æþ®†° Eç³Äñý*WÝë¢Ææÿ$ ?
i. Listing of securities i. òÜMæü*ÅÇsîýË ÍíÜt…VŠü
ii. Jobbers and Brokers ii. gêºÆŠÿÞ Ðèþ$ÇÄæý$$ {»ZMæüÆŠÿÞ
iii. Private placement iii. [ò³OÐóþr$ õ³Ï‹ÜÐðþ$…sŒý
iv. Privileged subscriptions iv. {í³ÑÌôýgŒýyŠþ çÜ»Œý {íÜPç³Û¯ŒþÞ
Codes : MøyŠþÞ :
(A) i and ii (A) i Ðèþ$ÇÄæý$$ ii
(B) ii and iii (B) ii Ðèþ$ÇÄæý$$ iii
(C) iii and iv (C) iii Ðèþ$ÇÄæý$$ iv
(D) i, ii, iii and iv (D) i, ii, iii Ðèþ$ÇÄæý$$ iv
87. Assertion (A) : Blue chip shares are 87. °Ðóþ§æþ¯èþ (A) : º*Ï_‹³ ÐésêË$, ÝëtMŠü Ðèþ*ÆðÿPsŒý
listed on the stock exchange. gê¼™éÌZ ^óþÆæÿ$a™éÆæÿ$.
Reasoning (R) : Blue chip shares give M>Ææÿ×ý… (R) : º*Ï_‹³ ÐésêË$ °Ææÿ…™èþÆæÿ…V>
consistent high dividends. GMæü$PÐèþ yìþÑyðþ…yæþ$Ï Æÿ$$Ýë¢Æÿ$$.
Codes : MøyŠþÞ :
(A) Both (A) and (R) are right (A) (A) Ðèþ$ÇÄæý$$ (R) Æðÿ…yæþ* çÜÆðÿO¯èþÐóþ
(B) Both (A) and (R) are wrong (B) (A) Ðèþ$ÇÄæý$$ (R) Æðÿ…yæþ* çÜÆðÿO¯èþÑ M>§æþ$
(C) (A) is right but (R) is wrong (C) (A) çÜÆðÿO¯èþ§óþ M>± (R) çÜÆðÿO¯èþ¨ M>§æþ$
(D) (A) is wrong but (R) is right (D) (A) çÜÆðÿO¯èþ¨ M>§æþ$ M>± (R) çÜÆðÿO¯èþ¨
II 28 A-03-18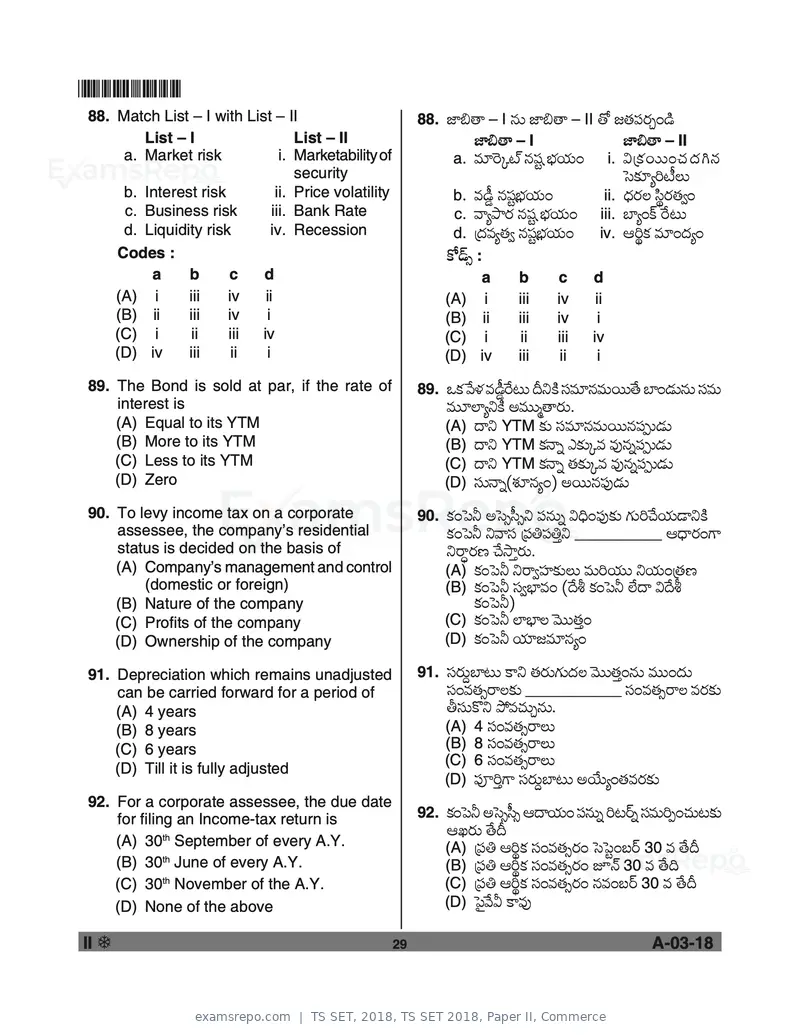
Text of page 29
*A0302*
88. Match List – I with List – II 88. gê¼™é – I ¯èþ$ gê¼™é – II ™ø f™èþç³Ææÿa…yìþ
List – I List – II gê¼™é – I gê¼™é – II
a. Market risk i. Marketability of a. Ðèþ*ÆðÿPsŒý ¯èþçÙt ¿æýÄæý$… i. Ñ{Mæ ü Æÿ$$…^è þ §æ þ W¯è þ
security òÜMæü*ÅÇsîýË$
b. Interest risk ii. Price volatility b. Ðèþyîþz ¯èþçÙt¿æýÄæý$… ii. «§æþÆæÿË íܦÆæÿ™èþÓ…
c. Business risk iii. Bank Rate c. ÐéÅ´ëÆæÿ ¯èþçÙt ¿æýÄæý$… iii. »êÅ…MŠü Æóÿr$
d. Liquidity risk iv. Recession d. {§æþÐèþÅ™èþÓ ¯èþçÙt¿æýÄæý$… iv. BǦMæü Ðèþ*…§æþÅ…
Codes : MøyŠþÞ :
a b c d a b c d
(A) i iii iv ii (A) i iii iv ii
(B) ii iii iv i (B) ii iii iv i
(C) i ii iii iv (C) i ii iii iv
(D) iv iii ii i (D) iv iii ii i
89. The Bond is sold at par, if the rate of 89. JMæü Ðóþâæý ÐèþyîþzÆóÿr$ ©°Mìü çÜÐèþ*¯èþÐèþ$Æÿ$$™óþ »ê…yæþ$¯èþ$ çÜÐèþ$
interest is Ðèþ$*ÌêÅ°Mìü AÐèþ$$ÙéÆæÿ$.
(A) Equal to its YTM (A) §é° YTM Mæü$ çÜÐèþ*¯èþÐèþ$Æÿ$$¯èþ糚yæþ$
(B) More to its YTM (B) §é° YTM Mæü¯é² GMæü$PÐèþ Ðèþ#¯èþ²ç³šyæþ$
(C) Less to its YTM (C) §é° YTM Mæü¯é² ™èþMæü$PÐèþ Ðèþ#¯èþ²ç³šyæþ$
(D) Zero (D) çÜ$¯é²(Ôèý*¯èþÅ…) AÆÿ$$¯èþç³#yæþ$
90. To levy income tax on a corporate 90. Mæü…ò³± AòÜÞïÜÞ° 糯èþ$² Ñ«¨…ç³#Mæü$ Væü$Ç^óþÄæý$yé°Mìü
assessee, the company’s residential Mæü…ò³± °ÐéçÜ {糆糆¢° __________ B«§éÆæÿ…V>
status is decided on the basis of °Æ>®Ææÿ×ý ^óþÝë¢Ææÿ$.
(A) Company’s management and control (A) Mæü…ò³± °Æ>ÓçßýMæü$Ë$ Ðèþ$ÇÄæý$$ °Äæý$…{™èþ×ý
(domestic or foreign) (B) Mæü…ò³± çÜÓ¿êÐèþ… (§óþÖ Mæü…ò³± Ìôý§é ѧóþÖ
(B) Nature of the company Mæü…ò³±)
(C) Profits of the company (C) Mæü…ò³± Ìê¿êË Ððþ$$™èþ¢…
(D) Ownership of the company (D) Mæü…ò³± Äæý*fÐèþ*¯èþÅ…
91. Depreciation which remains unadjusted 91. çÜÆæÿ$ª»êr$ M>° ™èþÆæÿ$Væü$§æþË Ððþ$$™èþ¢…¯èþ$ Ðèþ$$…§æþ$
can be carried forward for a period of çÜ…Ðèþ™èþÞÆ>ËMæü$ ___________ çÜ…Ðèþ™èþÞÆ>Ë ÐèþÆæÿMæü$
(A) 4 years ¡çÜ$Mö° ´ùÐèþ^èþ$a¯èþ$.
(B) 8 years (A) 4 çÜ…Ðèþ™èþÞÆ>Ë$
(C) 6 years (B) 8 çÜ…Ðèþ™èþÞÆ>Ë$
(C) 6 çÜ…Ðèþ™èþÞÆ>Ë$
(D) Till it is fully adjusted
(D) ç³NÇ¢V> çÜÆæÿ$ª»êr$ AÄôý$Å…™èþÐèþÆæÿMæü$
92. For a corporate assessee, the due date
for filing an Income-tax return is 92. Mæü…ò³± AòÜÞïÜÞ B§éÄæý$… 糯èþ$² ÇrÆŠÿ² çÜÐèþ$ǵ…^èþ$rMæü$
BQÆæÿ$ ™óþ©
(A) 30th September of every A.Y. (A) {糆 BǦMæü çÜ…Ðèþ™èþÞÆæÿ… òÜò³t…ºÆŠÿ 30 Ðèþ ™óþ©
(B) 30th June of every A.Y. (B) {糆 BǦMæü çÜ…Ðèþ™èþÞÆæÿ… l¯Œþ 30 Ðèþ ™óþ¨
(C) 30th November of the A.Y. (C) {糆 BǦMæü çÜ…Ðèþ™èþÞÆæÿ… ¯èþÐèþ…ºÆŠÿ 30 Ðèþ ™óþ©
(D) None of the above (D) ò³OÐóþÒ M>Ðèþ#
II 29 A-03-18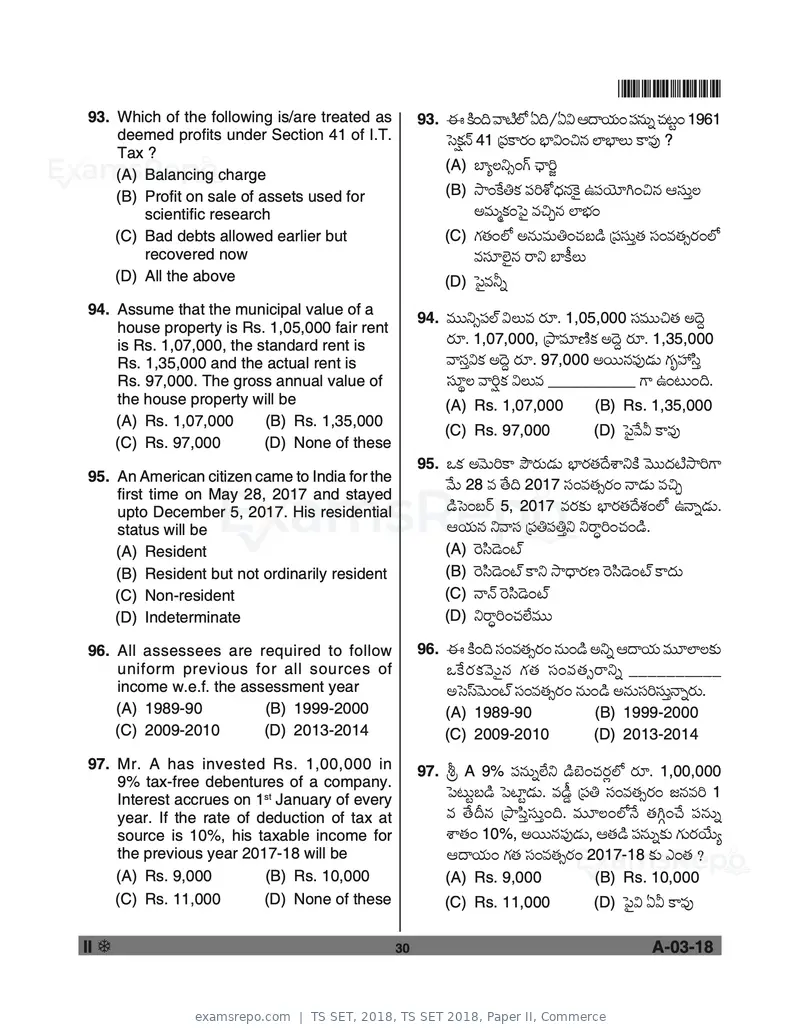
Text of page 30
*A0302*
93. Which of the following is/are treated as 93. D Mìü…¨ ÐésìýÌZ H¨/HÑ B§éÄæý$… 糯èþ$² ^èþrt… 1961
deemed profits under Section 41 of I.T. òÜMæüÛ¯Œþ 41 {ç³M>Ææÿ… ¿êÑ…_¯èþ Ìê¿êË$ M>Ðèþ# ?
Tax ?
(A) »êÅË°Þ…VŠü béÇj
(A) Balancing charge
(B) Profit on sale of assets used for (B) Ýë…Móü†Mæü ç³ÇÔZ«§æþ¯èþMðüO Eç³Äñý*W…_¯èþ BçÜ$¢Ë
scientific research AÐèþ$ÃMæü…ò³O Ðèþ_a¯èþ Ìê¿æý…
(C) Bad debts allowed earlier but (C) Væü™èþ…ÌZ A¯èþ$Ðèþ$†…^èþºyìþ {ç³çÜ$¢™èþ çÜ…Ðèþ™èþÞÆæÿ…ÌZ
recovered now ÐèþçÜ*ÌñýO¯èþ Æ>° »êMîüË$
(D) All the above (D) ò³OÐèþ±²
94. Assume that the municipal value of a
94. Ðèþ$$°Þç³ÌŒý ÑË$Ðèþ Ææÿ*. 1,05,000 çÜÐèþ$$_™èþ A§ðþª
house property is Rs. 1,05,000 fair rent
is Rs. 1,07,000, the standard rent is Ææÿ*. 1,07,000, {´ëÐèþ*×ìýMæü A§ðþª Ææÿ*. 1,35,000
Rs. 1,35,000 and the actual rent is ÐéçÜ¢ÑMæü A§ðþª Ææÿ*. 97,000 AÆÿ$$¯èþç³#yæþ$ Væü–àíÜ¢
Rs. 97,000. The gross annual value of çÜ*¦Ë ÐéÇÛMæü ÑË$Ðèþ __________ V> E…r$…¨.
the house property will be (A) Rs. 1,07,000 (B) Rs. 1,35,000
(A) Rs. 1,07,000 (B) Rs. 1,35,000
(C) Rs. 97,000 (D) ò³OÐóþÒ M>Ðèþ#
(C) Rs. 97,000 (D) None of these
95. JMæü AÐðþ$ÇM> ´ûÆæÿ$yæþ$ ¿êÆæÿ™èþ§óþÔ>°Mìü Ððþ$$§æþsìýÝëÇV>
95. An American citizen came to India for the
first time on May 28, 2017 and stayed
Ðóþ$ 28 Ðèþ ™óþ¨ 2017 çÜ…Ðèþ™èþÞÆæÿ… ¯éyæþ$ Ðèþ_a
upto December 5, 2017. His residential yìþòÜ…ºÆŠÿ 5, 2017 ÐèþÆæÿMæü$ ¿êÆæÿ™èþ§óþÔèý…ÌZ E¯é²yæþ$.
status will be BÄæý$¯èþ °ÐéçÜ {糆糆¢° °Æ>®Ç…^èþ…yìþ.
(A) Resident (A) ÆðÿíÜyðþ…sŒý
(B) Resident but not ordinarily resident (B) ÆðÿíÜyðþ…sŒý M>° Ý뫧éÆæÿ×ý ÆðÿíÜyðþ…sŒý M>§æþ$
(C) Non-resident (C) ¯é¯Œþ ÆðÿíÜyðþ…sŒý
(D) Indeterminate (D) °Æ>®Ç…^èþÌôýÐèþ$$
96. All assessees are required to follow 96. D Mìü…¨ çÜ…Ðèþ™èþÞÆæÿ… ¯èþ$…yìþ A°² B§éÄæý$ Ðèþ$*ÌêËMæü$
uniform previous for all sources of JMóüÆæÿMæüÐðþ$O¯èþ Væü™èþ çÜ…Ðèþ™èþÞÆ>°² __________
income w.e.f. the assessment year AòÜ‹ÜÐðþ$…sŒý çÜ…Ðèþ™èþÞÆæÿ… ¯èþ$…yìþ A¯èþ$çÜÇçÜ$¢¯é²Ææÿ$.
(A) 1989-90 (B) 1999-2000 (A) 1989-90 (B) 1999-2000
(C) 2009-2010 (D) 2013-2014 (C) 2009-2010 (D) 2013-2014
97. Mr. A has invested Rs. 1,00,000 in 97. } A 9% 糯èþ$²Ìôý° yìþ»ñý…^èþÆæÿÏÌZ Ææÿ*. 1,00,000
9% tax-free debentures of a company.
Interest accrues on 1st January of every ò³r$tºyìþ ò³sêtyæþ$. Ðèþyîþz {糆 çÜ…Ðèþ™èþÞÆæÿ… f¯èþÐèþÇ 1
year. If the rate of deduction of tax at Ðèþ ™óþ©¯èþ {´ëí³¢çÜ$¢…¨. Ðèþ$*Ë…ÌZ¯óþ ™èþWY…^óþ 糯èþ$²
source is 10%, his taxable income for Ô>™èþ… 10%, AÆÿ$$¯èþç³#yæþ$, B™èþyìþ 糯èþ$²Mæü$ Væü$ÆæÿÄôý$Å
the previous year 2017-18 will be B§éÄæý$… Væü™èþ çÜ…Ðèþ™èþÞÆæÿ… 2017-18 Mæü$ G…™èþ ?
(A) Rs. 9,000 (B) Rs. 10,000 (A) Rs. 9,000 (B) Rs. 10,000
(C) Rs. 11,000 (D) None of these (C) Rs. 11,000 (D) ò³OÑ HÒ M>Ðèþ#
II 30 A-03-18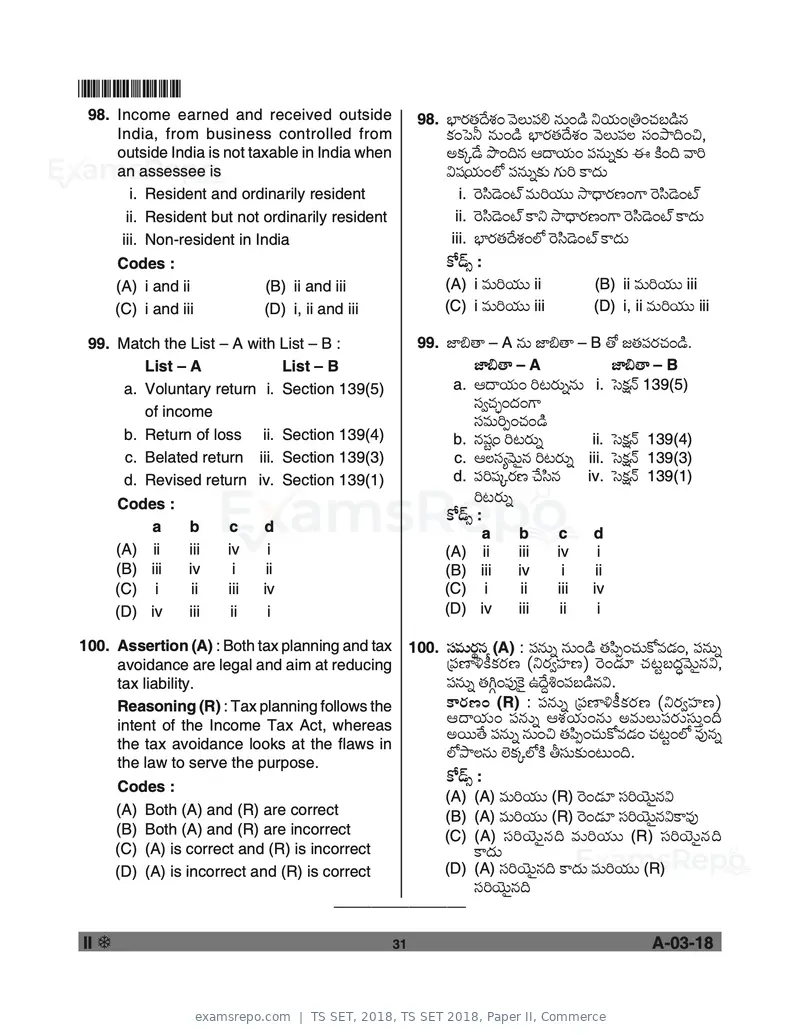
Text of page 31
*A0302*
98. Income earned and received outside 98. ¿êÆæÿ™èþ§óþÔèý… ÐðþË$ç³Í ¯èþ$…yìþ °Äæý$…{†…^èþºyìþ¯èþ
India, from business controlled from Mæü…ò³± ¯èþ$…yìþ ¿êÆæÿ™èþ§óþÔèý… ÐðþË$ç³Ë çÜ…´ë¨…_,
outside India is not taxable in India when AMæüPyóþ ´÷…¨¯èþ B§éÄæý$… 糯èþ$²Mæü$ D Mìü…¨ ÐéÇ
an assessee is ÑçÙÄæý$…ÌZ 糯èþ$²Mæü$ Væü$Ç M>§æþ$
i. Resident and ordinarily resident i. ÆðÿíÜyðþ…sŒý Ðèþ$ÇÄæý$$ Ý뫧éÆæÿ×ý…V> ÆðÿíÜyðþ…sŒý
ii. Resident but not ordinarily resident ii. ÆðÿíÜyðþ…sŒý M>° Ý뫧éÆæÿ×ý…V> ÆðÿíÜyðþ…sŒý M>§æþ$
iii. Non-resident in India iii. ¿êÆæÿ™èþ§óþÔèý…ÌZ ÆðÿíÜyðþ…sŒý M>§æþ$
Codes : MøyŠþÞ :
(A) i and ii (B) ii and iii (A) i Ðèþ$ÇÄæý$$ ii (B) ii Ðèþ$ÇÄæý$$ iii
(C) i and iii (D) i, ii and iii (C) i Ðèþ$ÇÄæý$$ iii (D) i, ii Ðèþ$ÇÄæý$$ iii
99. Match the List – A with List – B : 99. gê¼™é – A ¯èþ$ gê¼™é – B ™ø f™èþç³Ææÿ^èþ…yìþ.
List – A List – B gê¼™é – A gê¼™é – B
a. Voluntary return i. Section 139(5) a. B§éÄæý$… ÇrÆæÿ$²¯èþ$ i. òÜ„æü¯Œþ 139(5)
çÜÓ^èþe…§æþ…V>
of income
çÜÐèþ$ǵ…^èþ…yìþ
b. Return of loss ii. Section 139(4) b. ¯èþçÙt… ÇrÆæÿ$² ii. òÜ„æü¯Œþ 139(4)
c. Belated return iii. Section 139(3) c. BËçÜÅÐðþ$O¯èþ ÇrÆæÿ$² iii. òÜ„æü¯Œþ 139(3)
d. Revised return iv. Section 139(1) d. ç³ÇçÙPÆæÿ×ý ^óþíܯèþ iv. òÜ„æü¯Œþ 139(1)
Codes : ÇrÆæÿ$²
MøyŠþÞ :
a b c d a b c d
(A) ii iii iv i (A) ii iii iv i
(B) iii iv i ii (B) iii iv i ii
(C) i ii iii iv (C) i ii iii iv
(D) iv iii ii i (D) iv iii ii i
100. Assertion (A) : Both tax planning and tax 100. çÜÐèþ$Ææÿ¦¯èþ (A) : 糯èþ$² ¯èþ$…yìþ ™èþí³µ…^èþ$MøÐèþyæþ…, 糯èþ$²
avoidance are legal and aim at reducing {ç³×êãMîüMæüÆæÿ×ý (°ÆæÿÓçßý×ý) Æðÿ…yæþ* ^èþrtº§æþ®Ððþ$O¯èþÑ,
tax liability. 糯èþ$² ™èþWY…ç³#MðüO E§óþªÕ…糺yìþ¯èþÑ.
Reasoning (R) : Tax planning follows the M>Ææÿ×ý… (R) : 糯èþ$² {ç³×êãMîüMæüÆæÿ×ý (°ÆæÿÓçßý×ý)
intent of the Income Tax Act, whereas B§éÄæý$… 糯èþ$² BÔèýÄæý$…¯èþ$ AÐèþ$Ë$ç³Ææÿ$çÜ$¢…¨
the tax avoidance looks at the flaws in
AÆÿ$$™óþ 糯èþ$² ¯èþ$…_ ™èþí³µ…^èþ$MøÐèþyæþ… ^èþrt…ÌZ Ðèþ#¯èþ²
the law to serve the purpose.
ÌZ´ë˯èþ$ ÌñýMæüPÌZMìü ¡çÜ$Mæü$…r$…¨.
MøyŠþÞ :
Codes :
(A) (A) Ðèþ$ÇÄæý$$ (R) Æðÿ…yæþ* çÜÇÄñý$O¯èþÑ
(A) Both (A) and (R) are correct (B) (A) Ðèþ$ÇÄæý$$ (R) Æðÿ…yæþ* çÜÇÄñý$O¯èþÑM>Ðèþ#
(B) Both (A) and (R) are incorrect (C) (A) çÜÇÄñý$O¯èþ¨ Ðèþ$ÇÄæý$$ (R) çÜÇÄñý$O¯èþ¨
(C) (A) is correct and (R) is incorrect M>§æþ$
(D) (A) is incorrect and (R) is correct (D) (A) çÜÇÄñý$O¯èþ¨ M>§æþ$ Ðèþ$ÇÄæý$$ (R)
çÜÇÄñý$O¯èþ¨
______________
II 31 A-03-18
Text of page 32
*A0318*
Space for Rough Work
II 32 A-03-18Official key not published for this paper.
Page 1 of 32
Source: Telangana State Eligibility Test. Question paper published by Telangana State Eligibility Test.